Three-stage timeline showing a property survey is too early at offer accepted, ideal once the mortgage offer is in place and too late just before exchange

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

When and Why to Get a Property Survey – Beyond the Mortgage Valuation

Three-stage timeline showing a property survey is too early at offer accepted, ideal once the mortgage offer is in place and too late just before exchange

Would you spend £500 to avoid a £10,000 mistake?

That’s the kind of risk property surveys are designed to manage. While a mortgage valuation checks if a home is suitable for lending, a survey digs deeper into the property itself — helping buyers make confident, informed decisions.

This article explains the difference between a mortgage valuation and an independent survey, outlines the options available, and explores when it makes most sense to get one. We also look at how surveys can affect real purchase decisions, including two case studies from our clients.

The Mortgage Valuation – For the Lender, Not for You

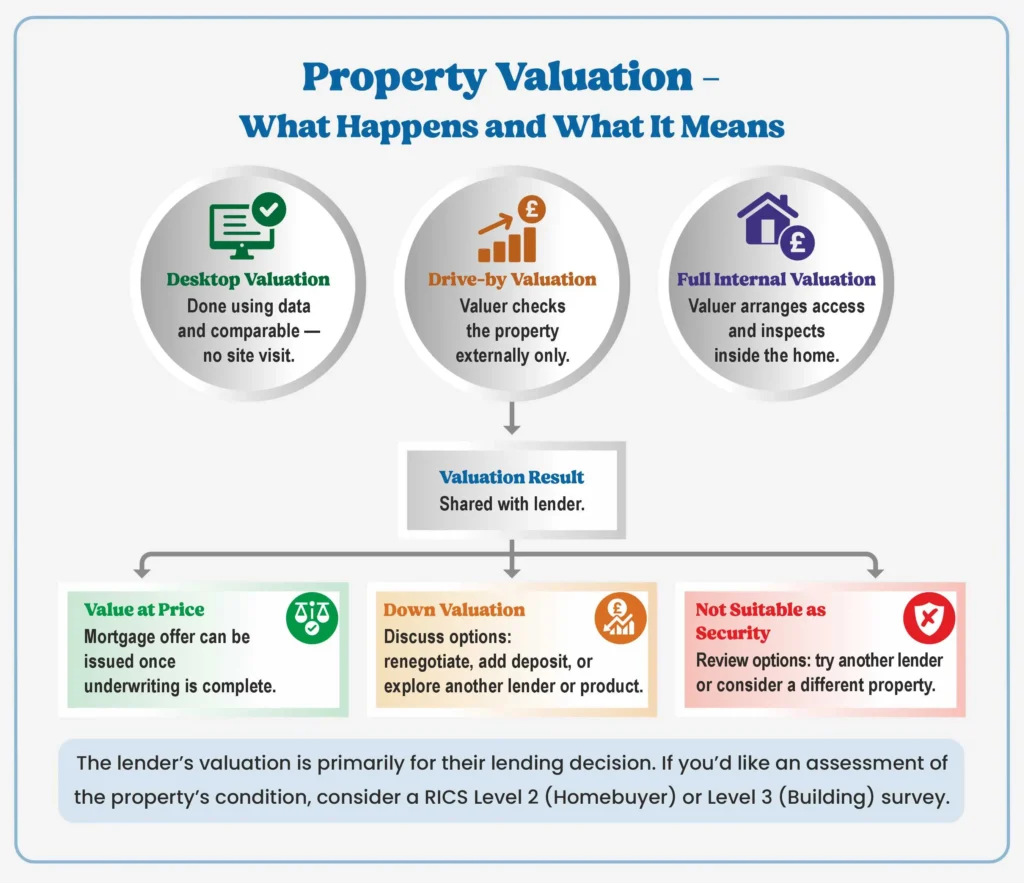
Every mortgage lender will instruct a valuation before offering a mortgage. The purpose is limited to:

  • Confirming the property is worth the agreed purchase price.
  • Checking it is suitable security for lending.

The lender’s concern is simple: if the property had to be repossessed, would it sell easily? This valuation is written for the lender’s benefit, not yours. It does not comment on the condition of the roof, electrics, plumbing, or potential repair costs.

Why Buyers Commission Their Own Survey

As a buyer, it’s sensible to want more reassurance. A private survey can:

  • Highlight structural issues or hidden defects.
  • Help you budget for repairs and improvements.
  • Provide evidence to renegotiate the purchase price.
  • Give peace of mind before making such a large financial commitment.

Timing Is Key
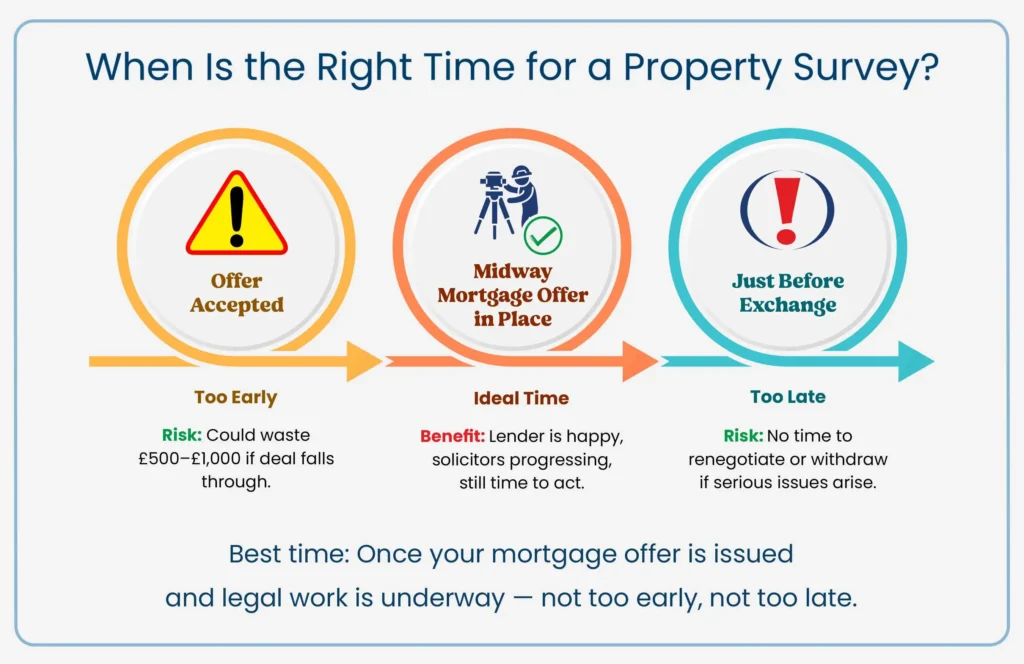
Three-stage timeline showing a property survey is too early at offer accepted, ideal once the mortgage offer is in place and too late just before exchange

We often see buyers keen to order a survey as soon as their offer is accepted. At Nachu Finance, our advice is usually to wait — but not too long.

  • Too early: Commissioning a survey before the mortgage offer or before solicitors have progressed can mean wasting £500–£1,000 if the purchase collapses.
  • Too late: Leaving it until just before exchange means you may not have time to renegotiate or withdraw if serious issues emerge.

Best timing: Once the mortgage offer is in place and legal checks are progressing, but still with enough time to act on the findings.

Think of it as a mid-transaction step — not too early, not too late.

Be Prepared

When commissioning a survey, it’s important to set realistic expectations.

  • Older properties will show wear and tear. A detailed report is likely to highlight age-related issues, and it’s rare for a survey to declare that everything is perfect. This doesn’t necessarily mean the property is a poor choice — just that maintenance will be part of ownership.
  • Not all sellers will negotiate. While some buyers successfully use survey findings to reduce the price, others find sellers unwilling to budge. Sellers may argue that the property’s age and condition have already been factored into the agreed price.

Think of the survey less as a bargaining tool and more as peace of mind — a way to understand exactly what you’re buying, plan for repairs, and proceed with confidence

Types of Property Survey

Survey Level Best For What It Includes Typical Cost
Level 1
(Condition Report)
Newer, standard homes in good condition Basic overview of construction and condition, highlights urgent defects, risks, or legal issues From a few hundred pounds
Level 2
(HomeBuyer Report)
Conventional properties in reasonable condition More detail on defects and maintenance; two versions: survey only or survey + valuation (includes market value & rebuild cost) £500–£700
Level 3
(Building Survey)
Older, larger, unusual, altered, or run-down properties; also if planning major works Most comprehensive – in-depth analysis, repair advice, timelines, and consequences of not acting £700–£1,000+

Summary

  • Level 1 = reassurance for newer, standard homes.
  • Level 2 = detailed check, suitable for most buyers.
  • Level 3 = full structural insight, essential for older or complex properties.

Whatever the level, always use a RICS-accredited surveyor to ensure the report meets professional standards. You can find approved firms at ricsfirms.com.

Special Case: New Build Properties

For new build homes, the situation is different. These properties usually come with a 10-year new build warranty, which covers structural defects. Since everything is brand new, a full structural survey is often unnecessary.

What can be useful is a snagging survey. This is carried out once the property is complete and checks for smaller defects or finishing issues — often called “snagging items.” These need to be reported within the developer’s defect liability period so that they are fixed at no cost to you. While optional, a snagging survey provides extra reassurance that the build quality has been independently checked.

Felix’s full Building Survey revealed several urgent repairs, with the cost of immediate works estimated at around £12,000. Using this report as evidence, Felix negotiated with the seller via the estate agent and secured a £6,000 reduction in the purchase price. This allowed him to proceed with confidence, knowing he had funds available to cover the essential repairs.

Alfred and Eva had already received their mortgage offer, but when they commissioned a full survey, several red flags were raised. The report highlighted serious issues with the conservatory and concerns over the electrical, gas and heating systems, which lacked up-to-date safety certification. Faced with the likelihood of costly repairs and ongoing risks, they chose to walk away from the purchase and later found another property that passed its survey without major issues.

How to Find a Surveyor

When arranging your own survey, always ensure the professional is RICS-qualified. There’s no single surveyor we recommend, as our clients buy across the UK. Instead:

  • Search for RICS-accredited firms in your area: www.ricsfirms.com
  • Compare quotes, reviews, and timescales.
  • Choose someone you feel comfortable with.

Frequently Asked Questions

Yes — even well-presented homes can hide issues such as damp, poor wiring, or structural weaknesses that aren’t visible at first glance.

No, a survey isn’t mandatory. The lender’s valuation is compulsory for the mortgage, but a survey is your choice. It’s strongly recommended to protect your investment.

Not usually. A private survey is for your use only. The lender relies on their own valuation unless you explicitly choose to share the report.

{“type”:”elementor”,”siteurl”:”https://nachufinance.co.uk/wp-json/”,”elements”:[{“id”:”1074679″,”elType”:”widget”,”isInner”:false,”isLocked”:false,”settings”:{“title”:”How to Find a Surveyor”,”title_color”:”#222222″,”typography_typography”:”custom”,”typography_font_family”:”Poppins”,”typography_font_size”:{“unit”:”px”,”size”:20,”sizes”:[]},”typography_font_weight”:”600″,”typography_line_height”:{“unit”:”px”,”size”:24,”sizes”:[]},”_margin”:{“unit”:”px”,”top”:”0″,”right”:”0″,”bottom”:”0″,”left”:”0″,”isLinked”:false},”_padding”:{“unit”:”px”,”top”:”0″,”right”:”0″,”bottom”:”0″,”left”:”0″,”isLinked”:false},”link”:{“url”:””,”is_external”:””,”nofollow”:””,”custom_attributes”:””},”size”:”default”,”header_size”:”h2″,”align”:””,”align_tablet”:””,”align_mobile”:””,”typography_font_size_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_font_size_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_text_transform”:””,”typography_font_style”:””,”typography_text_decoration”:””,”typography_line_height_tablet”:{“unit”:”em”,”size”:””,”sizes”:[]},”typography_line_height_mobile”:{“unit”:”em”,”size”:””,”sizes”:[]},”typography_letter_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_letter_spacing_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_letter_spacing_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_word_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_word_spacing_tablet”:{“unit”:”em”,”size”:””,”sizes”:[]},”typography_word_spacing_mobile”:{“unit”:”em”,”size”:””,”sizes”:[]},”text_stroke_text_stroke_type”:””,”text_stroke_text_stroke”:{“unit”:”px”,”size”:””,”sizes”:[]},”text_stroke_text_stroke_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”text_stroke_text_stroke_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”text_stroke_stroke_color”:”#000″,”text_shadow_text_shadow_type”:””,”text_shadow_text_shadow”:{“horizontal”:0,”vertical”:0,”blur”:10,”color”:”rgba(0,0,0,0.3)”},”blend_mode”:””,”title_hover_color”:””,”title_hover_color_transition_duration”:{“unit”:”s”,”size”:””,”sizes”:[]},”_title”:””,”_margin_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_margin_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_padding_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_padding_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_element_width”:””,”_element_width_tablet”:””,”_element_width_mobile”:””,”_element_custom_width”:{“unit”:”%”,”size”:””,”sizes”:[]},”_element_custom_width_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_element_custom_width_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_grid_column”:””,”_grid_column_tablet”:””,”_grid_column_mobile”:””,”_grid_column_custom”:””,”_grid_column_custom_tablet”:””,”_grid_column_custom_mobile”:””,”_grid_row”:””,”_grid_row_tablet”:””,”_grid_row_mobile”:””,”_grid_row_custom”:””,”_grid_row_custom_tablet”:””,”_grid_row_custom_mobile”:””,”_flex_align_self”:””,”_flex_align_self_tablet”:””,”_flex_align_self_mobile”:””,”_flex_order”:””,”_flex_order_tablet”:””,”_flex_order_mobile”:””,”_flex_order_custom”:””,”_flex_order_custom_tablet”:””,”_flex_order_custom_mobile”:””,”_flex_size”:””,”_flex_size_tablet”:””,”_flex_size_mobile”:””,”_flex_grow”:1,”_flex_grow_tablet”:””,”_flex_grow_mobile”:””,”_flex_shrink”:1,”_flex_shrink_tablet”:””,”_flex_shrink_mobile”:””,”_element_vertical_align”:””,”_element_vertical_align_tablet”:””,”_element_vertical_align_mobile”:””,”_position”:””,”_offset_orientation_h”:”start”,”_offset_x”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_x_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_x_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_x_end”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_x_end_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_x_end_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_orientation_v”:”start”,”_offset_y”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_y_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_y_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_y_end”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_y_end_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_y_end_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_z_index”:””,”_z_index_tablet”:””,”_z_index_mobile”:””,”_element_id”:””,”_css_classes”:””,”e_display_conditions”:””,”_element_cache”:””,”motion_fx_motion_fx_scrolling”:””,”motion_fx_translateY_effect”:””,”motion_fx_translateY_direction”:””,”motion_fx_translateY_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”motion_fx_translateY_affectedRange”:{“unit”:”%”,”size”:””,”sizes”:{“start”:0,”end”:100}},”motion_fx_translateX_effect”:””,”motion_fx_translateX_direction”:””,”motion_fx_translateX_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”motion_fx_translateX_affectedRange”:{“unit”:”%”,”size”:””,”sizes”:{“start”:0,”end”:100}},”motion_fx_opacity_effect”:””,”motion_fx_opacity_direction”:”out-in”,”motion_fx_opacity_level”:{“unit”:”px”,”size”:10,”sizes”:[]},”motion_fx_opacity_range”:{“unit”:”%”,”size”:””,”sizes”:{“start”:20,”end”:80}},”motion_fx_blur_effect”:””,”motion_fx_blur_direction”:”out-in”,”motion_fx_blur_level”:{“unit”:”px”,”size”:7,”sizes”:[]},”motion_fx_blur_range”:{“unit”:”%”,”size”:””,”sizes”:{“start”:20,”end”:80}},”motion_fx_rotateZ_effect”:””,”motion_fx_rotateZ_direction”:””,”motion_fx_rotateZ_speed”:{“unit”:”px”,”size”:1,”sizes”:[]},”motion_fx_rotateZ_affectedRange”:{“unit”:”%”,”size”:””,”sizes”:{“start”:0,”end”:100}},”motion_fx_scale_effect”:””,”motion_fx_scale_direction”:”out-in”,”motion_fx_scale_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”motion_fx_scale_range”:{“unit”:”%”,”size”:””,”sizes”:{“start”:20,”end”:80}},”motion_fx_transform_origin_x”:”center”,”motion_fx_transform_origin_y”:”center”,”motion_fx_devices”:[“desktop”,”tablet”,”mobile”],”motion_fx_range”:””,”motion_fx_motion_fx_mouse”:””,”motion_fx_mouseTrack_effect”:””,”motion_fx_mouseTrack_direction”:””,”motion_fx_mouseTrack_speed”:{“unit”:”px”,”size”:1,”sizes”:[]},”motion_fx_tilt_effect”:””,”motion_fx_tilt_direction”:””,”motion_fx_tilt_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”handle_motion_fx_asset_loading”:””,”sticky”:””,”sticky_on”:[“desktop”,”tablet”,”mobile”],”sticky_offset”:0,”sticky_offset_tablet”:””,”sticky_offset_mobile”:””,”sticky_effects_offset”:0,”sticky_effects_offset_tablet”:””,”sticky_effects_offset_mobile”:””,”sticky_anchor_link_offset”:0,”sticky_anchor_link_offset_tablet”:””,”sticky_anchor_link_offset_mobile”:””,”sticky_parent”:””,”_animation”:””,”_animation_tablet”:””,”_animation_mobile”:””,”animation_duration”:””,”_animation_delay”:””,”_transform_rotate_popover”:””,”_transform_rotateZ_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotate_3d”:””,”_transform_rotateX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_perspective_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translate_popover”:””,”_transform_translateX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_popover”:””,”_transform_keep_proportions”:”yes”,”_transform_scale_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skew_popover”:””,”_transform_skewX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewX_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewX_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewY_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_flipX_effect”:””,”_transform_flipY_effect”:””,”_transform_rotate_popover_hover”:””,”_transform_rotateZ_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotate_3d_hover”:””,”_transform_rotateX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_perspective_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translate_popover_hover”:””,”_transform_translateX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_popover_hover”:””,”_transform_keep_proportions_hover”:”yes”,”_transform_scale_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skew_popover_hover”:””,”_transform_skewX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewX_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewX_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewY_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_flipX_effect_hover”:””,”_transform_flipY_effect_hover”:””,”_transform_transition_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”motion_fx_transform_x_anchor_point”:””,”motion_fx_transform_x_anchor_point_tablet”:””,”motion_fx_transform_x_anchor_point_mobile”:””,”motion_fx_transform_y_anchor_point”:””,”motion_fx_transform_y_anchor_point_tablet”:””,”motion_fx_transform_y_anchor_point_mobile”:””,”_background_background”:””,”_background_color”:””,”_background_color_stop”:{“unit”:”%”,”size”:0,”sizes”:[]},”_background_color_stop_tablet”:{“unit”:”%”},”_background_color_stop_mobile”:{“unit”:”%”},”_background_color_b”:”#f2295b”,”_background_color_b_stop”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_color_b_stop_tablet”:{“unit”:”%”},”_background_color_b_stop_mobile”:{“unit”:”%”},”_background_gradient_type”:”linear”,”_background_gradient_angle”:{“unit”:”deg”,”size”:180,”sizes”:[]},”_background_gradient_angle_tablet”:{“unit”:”deg”},”_background_gradient_angle_mobile”:{“unit”:”deg”},”_background_gradient_position”:”center center”,”_background_gradient_position_tablet”:””,”_background_gradient_position_mobile”:””,”_background_image”:{“url”:””,”id”:””,”size”:””},”_background_image_tablet”:{“url”:””,”id”:””,”size”:””},”_background_image_mobile”:{“url”:””,”id”:””,”size”:””},”_background_position”:””,”_background_position_tablet”:””,”_background_position_mobile”:””,”_background_xpos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_xpos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_xpos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_ypos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_ypos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_ypos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_attachment”:””,”_background_repeat”:””,”_background_repeat_tablet”:””,”_background_repeat_mobile”:””,”_background_size”:””,”_background_size_tablet”:””,”_background_size_mobile”:””,”_background_bg_width”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_bg_width_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_bg_width_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_video_link”:””,”_background_video_start”:””,”_background_video_end”:””,”_background_play_once”:””,”_background_play_on_mobile”:””,”_background_privacy_mode”:””,”_background_video_fallback”:{“url”:””,”id”:””,”size”:””},”_background_slideshow_gallery”:[],”_background_slideshow_loop”:”yes”,”_background_slideshow_slide_duration”:5000,”_background_slideshow_slide_transition”:”fade”,”_background_slideshow_transition_duration”:500,”_background_slideshow_background_size”:””,”_background_slideshow_background_size_tablet”:””,”_background_slideshow_background_size_mobile”:””,”_background_slideshow_background_position”:””,”_background_slideshow_background_position_tablet”:””,”_background_slideshow_background_position_mobile”:””,”_background_slideshow_lazyload”:””,”_background_slideshow_ken_burns”:””,”_background_slideshow_ken_burns_zoom_direction”:”in”,”_background_hover_background”:””,”_background_hover_color”:””,”_background_hover_color_stop”:{“unit”:”%”,”size”:0,”sizes”:[]},”_background_hover_color_stop_tablet”:{“unit”:”%”},”_background_hover_color_stop_mobile”:{“unit”:”%”},”_background_hover_color_b”:”#f2295b”,”_background_hover_color_b_stop”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_hover_color_b_stop_tablet”:{“unit”:”%”},”_background_hover_color_b_stop_mobile”:{“unit”:”%”},”_background_hover_gradient_type”:”linear”,”_background_hover_gradient_angle”:{“unit”:”deg”,”size”:180,”sizes”:[]},”_background_hover_gradient_angle_tablet”:{“unit”:”deg”},”_background_hover_gradient_angle_mobile”:{“unit”:”deg”},”_background_hover_gradient_position”:”center center”,”_background_hover_gradient_position_tablet”:””,”_background_hover_gradient_position_mobile”:””,”_background_hover_image”:{“url”:””,”id”:””,”size”:””},”_background_hover_image_tablet”:{“url”:””,”id”:””,”size”:””},”_background_hover_image_mobile”:{“url”:””,”id”:””,”size”:””},”_background_hover_position”:””,”_background_hover_position_tablet”:””,”_background_hover_position_mobile”:””,”_background_hover_xpos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_xpos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_xpos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_ypos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_ypos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_ypos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_attachment”:””,”_background_hover_repeat”:””,”_background_hover_repeat_tablet”:””,”_background_hover_repeat_mobile”:””,”_background_hover_size”:””,”_background_hover_size_tablet”:””,”_background_hover_size_mobile”:””,”_background_hover_bg_width”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_hover_bg_width_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_hover_bg_width_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_hover_video_link”:””,”_background_hover_video_start”:””,”_background_hover_video_end”:””,”_background_hover_play_once”:””,”_background_hover_play_on_mobile”:””,”_background_hover_privacy_mode”:””,”_background_hover_video_fallback”:{“url”:””,”id”:””,”size”:””},”_background_hover_slideshow_gallery”:[],”_background_hover_slideshow_loop”:”yes”,”_background_hover_slideshow_slide_duration”:5000,”_background_hover_slideshow_slide_transition”:”fade”,”_background_hover_slideshow_transition_duration”:500,”_background_hover_slideshow_background_size”:””,”_background_hover_slideshow_background_size_tablet”:””,”_background_hover_slideshow_background_size_mobile”:””,”_background_hover_slideshow_background_position”:””,”_background_hover_slideshow_background_position_tablet”:””,”_background_hover_slideshow_background_position_mobile”:””,”_background_hover_slideshow_lazyload”:””,”_background_hover_slideshow_ken_burns”:””,”_background_hover_slideshow_ken_burns_zoom_direction”:”in”,”_background_hover_transition”:{“unit”:”px”,”size”:””,”sizes”:[]},”_border_border”:””,”_border_width”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_width_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_width_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_color”:””,”_border_radius”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_box_shadow_box_shadow_type”:””,”_box_shadow_box_shadow”:{“horizontal”:0,”vertical”:0,”blur”:10,”spread”:0,”color”:”rgba(0,0,0,0.5)”},”_box_shadow_box_shadow_position”:” “,”_border_hover_border”:””,”_border_hover_width”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_hover_width_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_hover_width_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_hover_color”:””,”_border_radius_hover”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_hover_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_hover_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_box_shadow_hover_box_shadow_type”:””,”_box_shadow_hover_box_shadow”:{“horizontal”:0,”vertical”:0,”blur”:10,”spread”:0,”color”:”rgba(0,0,0,0.5)”},”_box_shadow_hover_box_shadow_position”:” “,”_border_hover_transition”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_switch”:””,”_mask_shape”:”circle”,”_mask_image”:{“url”:””,”id”:””,”size”:””},”_mask_image_tablet”:{“url”:””,”id”:””,”size”:””},”_mask_image_mobile”:{“url”:””,”id”:””,”size”:””},”_mask_size”:”contain”,”_mask_size_tablet”:””,”_mask_size_mobile”:””,”_mask_size_scale”:{“unit”:”%”,”size”:100,”sizes”:[]},”_mask_size_scale_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_size_scale_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position”:”center center”,”_mask_position_tablet”:””,”_mask_position_mobile”:””,”_mask_position_x”:{“unit”:”%”,”size”:0,”sizes”:[]},”_mask_position_x_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position_x_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position_y”:{“unit”:”%”,”size”:0,”sizes”:[]},”_mask_position_y_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position_y_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_repeat”:”no-repeat”,”_mask_repeat_tablet”:””,”_mask_repeat_mobile”:””,”hide_desktop”:””,”hide_tablet”:””,”hide_mobile”:””,”_attributes”:””,”custom_css”:””},”defaultEditSettings”:{“defaultEditRoute”:”content”},”interactions”:{},”elements”:[],”widgetType”:”heading”,”htmlCache”:””,”editSettings”:{“defaultEditRoute”:”content”,”panel”:{“activeTab”:”content”,”activeSection”:”section_title”}}},{“id”:”1aad907″,”elType”:”widget”,”isInner”:false,”isLocked”:false,”settings”:{“width”:{“unit”:”px”,”size”:50,”sizes”:[]},”text”:”Divider”,”weight”:{“unit”:”px”,”size”:5,”sizes”:[]},”gap”:{“unit”:”px”,”size”:””,”sizes”:[]},”_margin”:{“unit”:”px”,”top”:”-5″,”right”:”2″,”bottom”:”0″,”left”:”0″,”isLinked”:false},”_padding”:{“unit”:”px”,”top”:”0″,”right”:”0″,”bottom”:”0″,”left”:”0″,”isLinked”:false},”_background_color”:”#18BA60″,”_element_custom_width”:{“unit”:”px”,”size”:50,”sizes”:[]},”align”:”left”,”__globals__”:{“color”:”globals/colors?id=accent”},”style”:”solid”,”separator_type”:”pattern”,”pattern_spacing_flag”:”no-spacing”,”pattern_round_flag”:”bg-round”,”width_tablet”:{“unit”:”%”,”size”:””,”sizes”:[]},”width_mobile”:{“unit”:”%”,”size”:””,”sizes”:[]},”align_tablet”:””,”align_mobile”:””,”look”:”line”,”html_tag”:”span”,”icon”:{“value”:”fas fa-star”,”library”:”fa-solid”},”color”:”#000″,”pattern_height”:{“unit”:”px”,”size”:20,”sizes”:[]},”pattern_size”:{“unit”:”px”,”size”:20,”sizes”:[]},”gap_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”gap_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”text_color”:””,”typography_typography”:””,”typography_font_family”:””,”typography_font_size”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_font_size_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_font_size_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_font_weight”:””,”typography_text_transform”:””,”typography_font_style”:””,”typography_text_decoration”:””,”typography_line_height”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_line_height_tablet”:{“unit”:”em”,”size”:””,”sizes”:[]},”typography_line_height_mobile”:{“unit”:”em”,”size”:””,”sizes”:[]},”typography_letter_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_letter_spacing_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_letter_spacing_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_word_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_word_spacing_tablet”:{“unit”:”em”,”size”:””,”sizes”:[]},”typography_word_spacing_mobile”:{“unit”:”em”,”size”:””,”sizes”:[]},”text_stroke_text_stroke_type”:””,”text_stroke_text_stroke”:{“unit”:”px”,”size”:””,”sizes”:[]},”text_stroke_text_stroke_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”text_stroke_text_stroke_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”text_stroke_stroke_color”:”#000″,”text_align”:”center”,”text_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”text_spacing_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”text_spacing_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”icon_view”:”default”,”icon_size”:{“unit”:”px”,”size”:””,”sizes”:[]},”icon_size_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”icon_size_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”icon_padding”:{“unit”:”px”,”size”:””,”sizes”:[]},”primary_color”:””,”secondary_color”:””,”icon_align”:”center”,”icon_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”icon_spacing_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”icon_spacing_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”rotate”:{“unit”:”deg”,”size”:””,”sizes”:[]},”rotate_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”rotate_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”icon_border_width”:{“unit”:”px”,”size”:””,”sizes”:[]},”border_radius”:{“unit”:”px”,”size”:””,”sizes”:[]},”_title”:””,”_margin_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_margin_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_padding_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_padding_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_element_width”:””,”_element_width_tablet”:””,”_element_width_mobile”:””,”_element_custom_width_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_element_custom_width_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_grid_column”:””,”_grid_column_tablet”:””,”_grid_column_mobile”:””,”_grid_column_custom”:””,”_grid_column_custom_tablet”:””,”_grid_column_custom_mobile”:””,”_grid_row”:””,”_grid_row_tablet”:””,”_grid_row_mobile”:””,”_grid_row_custom”:””,”_grid_row_custom_tablet”:””,”_grid_row_custom_mobile”:””,”_flex_align_self”:””,”_flex_align_self_tablet”:””,”_flex_align_self_mobile”:””,”_flex_order”:””,”_flex_order_tablet”:””,”_flex_order_mobile”:””,”_flex_order_custom”:””,”_flex_order_custom_tablet”:””,”_flex_order_custom_mobile”:””,”_flex_size”:””,”_flex_size_tablet”:””,”_flex_size_mobile”:””,”_flex_grow”:1,”_flex_grow_tablet”:””,”_flex_grow_mobile”:””,”_flex_shrink”:1,”_flex_shrink_tablet”:””,”_flex_shrink_mobile”:””,”_element_vertical_align”:””,”_element_vertical_align_tablet”:””,”_element_vertical_align_mobile”:””,”_position”:””,”_offset_orientation_h”:”start”,”_offset_x”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_x_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_x_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_x_end”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_x_end_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_x_end_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_orientation_v”:”start”,”_offset_y”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_y_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_y_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_y_end”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_y_end_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_y_end_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_z_index”:””,”_z_index_tablet”:””,”_z_index_mobile”:””,”_element_id”:””,”_css_classes”:””,”e_display_conditions”:””,”_element_cache”:””,”motion_fx_motion_fx_scrolling”:””,”motion_fx_translateY_effect”:””,”motion_fx_translateY_direction”:””,”motion_fx_translateY_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”motion_fx_translateY_affectedRange”:{“unit”:”%”,”size”:””,”sizes”:{“start”:0,”end”:100}},”motion_fx_translateX_effect”:””,”motion_fx_translateX_direction”:””,”motion_fx_translateX_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”motion_fx_translateX_affectedRange”:{“unit”:”%”,”size”:””,”sizes”:{“start”:0,”end”:100}},”motion_fx_opacity_effect”:””,”motion_fx_opacity_direction”:”out-in”,”motion_fx_opacity_level”:{“unit”:”px”,”size”:10,”sizes”:[]},”motion_fx_opacity_range”:{“unit”:”%”,”size”:””,”sizes”:{“start”:20,”end”:80}},”motion_fx_blur_effect”:””,”motion_fx_blur_direction”:”out-in”,”motion_fx_blur_level”:{“unit”:”px”,”size”:7,”sizes”:[]},”motion_fx_blur_range”:{“unit”:”%”,”size”:””,”sizes”:{“start”:20,”end”:80}},”motion_fx_rotateZ_effect”:””,”motion_fx_rotateZ_direction”:””,”motion_fx_rotateZ_speed”:{“unit”:”px”,”size”:1,”sizes”:[]},”motion_fx_rotateZ_affectedRange”:{“unit”:”%”,”size”:””,”sizes”:{“start”:0,”end”:100}},”motion_fx_scale_effect”:””,”motion_fx_scale_direction”:”out-in”,”motion_fx_scale_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”motion_fx_scale_range”:{“unit”:”%”,”size”:””,”sizes”:{“start”:20,”end”:80}},”motion_fx_transform_origin_x”:”center”,”motion_fx_transform_origin_y”:”center”,”motion_fx_devices”:[“desktop”,”tablet”,”mobile”],”motion_fx_range”:””,”motion_fx_motion_fx_mouse”:””,”motion_fx_mouseTrack_effect”:””,”motion_fx_mouseTrack_direction”:””,”motion_fx_mouseTrack_speed”:{“unit”:”px”,”size”:1,”sizes”:[]},”motion_fx_tilt_effect”:””,”motion_fx_tilt_direction”:””,”motion_fx_tilt_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”handle_motion_fx_asset_loading”:””,”sticky”:””,”sticky_on”:[“desktop”,”tablet”,”mobile”],”sticky_offset”:0,”sticky_offset_tablet”:””,”sticky_offset_mobile”:””,”sticky_effects_offset”:0,”sticky_effects_offset_tablet”:””,”sticky_effects_offset_mobile”:””,”sticky_anchor_link_offset”:0,”sticky_anchor_link_offset_tablet”:””,”sticky_anchor_link_offset_mobile”:””,”sticky_parent”:””,”_animation”:””,”_animation_tablet”:””,”_animation_mobile”:””,”animation_duration”:””,”_animation_delay”:””,”_transform_rotate_popover”:””,”_transform_rotateZ_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotate_3d”:””,”_transform_rotateX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_perspective_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translate_popover”:””,”_transform_translateX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_popover”:””,”_transform_keep_proportions”:”yes”,”_transform_scale_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skew_popover”:””,”_transform_skewX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewX_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewX_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewY_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_flipX_effect”:””,”_transform_flipY_effect”:””,”_transform_rotate_popover_hover”:””,”_transform_rotateZ_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotate_3d_hover”:””,”_transform_rotateX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_perspective_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translate_popover_hover”:””,”_transform_translateX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_popover_hover”:””,”_transform_keep_proportions_hover”:”yes”,”_transform_scale_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skew_popover_hover”:””,”_transform_skewX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewX_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewX_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewY_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_flipX_effect_hover”:””,”_transform_flipY_effect_hover”:””,”_transform_transition_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”motion_fx_transform_x_anchor_point”:””,”motion_fx_transform_x_anchor_point_tablet”:””,”motion_fx_transform_x_anchor_point_mobile”:””,”motion_fx_transform_y_anchor_point”:””,”motion_fx_transform_y_anchor_point_tablet”:””,”motion_fx_transform_y_anchor_point_mobile”:””,”_background_background”:””,”_background_color_stop”:{“unit”:”%”,”size”:0,”sizes”:[]},”_background_color_stop_tablet”:{“unit”:”%”},”_background_color_stop_mobile”:{“unit”:”%”},”_background_color_b”:”#f2295b”,”_background_color_b_stop”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_color_b_stop_tablet”:{“unit”:”%”},”_background_color_b_stop_mobile”:{“unit”:”%”},”_background_gradient_type”:”linear”,”_background_gradient_angle”:{“unit”:”deg”,”size”:180,”sizes”:[]},”_background_gradient_angle_tablet”:{“unit”:”deg”},”_background_gradient_angle_mobile”:{“unit”:”deg”},”_background_gradient_position”:”center center”,”_background_gradient_position_tablet”:””,”_background_gradient_position_mobile”:””,”_background_image”:{“url”:””,”id”:””,”size”:””},”_background_image_tablet”:{“url”:””,”id”:””,”size”:””},”_background_image_mobile”:{“url”:””,”id”:””,”size”:””},”_background_position”:””,”_background_position_tablet”:””,”_background_position_mobile”:””,”_background_xpos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_xpos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_xpos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_ypos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_ypos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_ypos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_attachment”:””,”_background_repeat”:””,”_background_repeat_tablet”:””,”_background_repeat_mobile”:””,”_background_size”:””,”_background_size_tablet”:””,”_background_size_mobile”:””,”_background_bg_width”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_bg_width_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_bg_width_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_video_link”:””,”_background_video_start”:””,”_background_video_end”:””,”_background_play_once”:””,”_background_play_on_mobile”:””,”_background_privacy_mode”:””,”_background_video_fallback”:{“url”:””,”id”:””,”size”:””},”_background_slideshow_gallery”:[],”_background_slideshow_loop”:”yes”,”_background_slideshow_slide_duration”:5000,”_background_slideshow_slide_transition”:”fade”,”_background_slideshow_transition_duration”:500,”_background_slideshow_background_size”:””,”_background_slideshow_background_size_tablet”:””,”_background_slideshow_background_size_mobile”:””,”_background_slideshow_background_position”:””,”_background_slideshow_background_position_tablet”:””,”_background_slideshow_background_position_mobile”:””,”_background_slideshow_lazyload”:””,”_background_slideshow_ken_burns”:””,”_background_slideshow_ken_burns_zoom_direction”:”in”,”_background_hover_background”:””,”_background_hover_color”:””,”_background_hover_color_stop”:{“unit”:”%”,”size”:0,”sizes”:[]},”_background_hover_color_stop_tablet”:{“unit”:”%”},”_background_hover_color_stop_mobile”:{“unit”:”%”},”_background_hover_color_b”:”#f2295b”,”_background_hover_color_b_stop”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_hover_color_b_stop_tablet”:{“unit”:”%”},”_background_hover_color_b_stop_mobile”:{“unit”:”%”},”_background_hover_gradient_type”:”linear”,”_background_hover_gradient_angle”:{“unit”:”deg”,”size”:180,”sizes”:[]},”_background_hover_gradient_angle_tablet”:{“unit”:”deg”},”_background_hover_gradient_angle_mobile”:{“unit”:”deg”},”_background_hover_gradient_position”:”center center”,”_background_hover_gradient_position_tablet”:””,”_background_hover_gradient_position_mobile”:””,”_background_hover_image”:{“url”:””,”id”:””,”size”:””},”_background_hover_image_tablet”:{“url”:””,”id”:””,”size”:””},”_background_hover_image_mobile”:{“url”:””,”id”:””,”size”:””},”_background_hover_position”:””,”_background_hover_position_tablet”:””,”_background_hover_position_mobile”:””,”_background_hover_xpos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_xpos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_xpos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_ypos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_ypos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_ypos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_attachment”:””,”_background_hover_repeat”:””,”_background_hover_repeat_tablet”:””,”_background_hover_repeat_mobile”:””,”_background_hover_size”:””,”_background_hover_size_tablet”:””,”_background_hover_size_mobile”:””,”_background_hover_bg_width”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_hover_bg_width_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_hover_bg_width_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_hover_video_link”:””,”_background_hover_video_start”:””,”_background_hover_video_end”:””,”_background_hover_play_once”:””,”_background_hover_play_on_mobile”:””,”_background_hover_privacy_mode”:””,”_background_hover_video_fallback”:{“url”:””,”id”:””,”size”:””},”_background_hover_slideshow_gallery”:[],”_background_hover_slideshow_loop”:”yes”,”_background_hover_slideshow_slide_duration”:5000,”_background_hover_slideshow_slide_transition”:”fade”,”_background_hover_slideshow_transition_duration”:500,”_background_hover_slideshow_background_size”:””,”_background_hover_slideshow_background_size_tablet”:””,”_background_hover_slideshow_background_size_mobile”:””,”_background_hover_slideshow_background_position”:””,”_background_hover_slideshow_background_position_tablet”:””,”_background_hover_slideshow_background_position_mobile”:””,”_background_hover_slideshow_lazyload”:””,”_background_hover_slideshow_ken_burns”:””,”_background_hover_slideshow_ken_burns_zoom_direction”:”in”,”_background_hover_transition”:{“unit”:”px”,”size”:””,”sizes”:[]},”_border_border”:””,”_border_width”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_width_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_width_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_color”:””,”_border_radius”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_box_shadow_box_shadow_type”:””,”_box_shadow_box_shadow”:{“horizontal”:0,”vertical”:0,”blur”:10,”spread”:0,”color”:”rgba(0,0,0,0.5)”},”_box_shadow_box_shadow_position”:” “,”_border_hover_border”:””,”_border_hover_width”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_hover_width_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_hover_width_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_hover_color”:””,”_border_radius_hover”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_hover_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_hover_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_box_shadow_hover_box_shadow_type”:””,”_box_shadow_hover_box_shadow”:{“horizontal”:0,”vertical”:0,”blur”:10,”spread”:0,”color”:”rgba(0,0,0,0.5)”},”_box_shadow_hover_box_shadow_position”:” “,”_border_hover_transition”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_switch”:””,”_mask_shape”:”circle”,”_mask_image”:{“url”:””,”id”:””,”size”:””},”_mask_image_tablet”:{“url”:””,”id”:””,”size”:””},”_mask_image_mobile”:{“url”:””,”id”:””,”size”:””},”_mask_size”:”contain”,”_mask_size_tablet”:””,”_mask_size_mobile”:””,”_mask_size_scale”:{“unit”:”%”,”size”:100,”sizes”:[]},”_mask_size_scale_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_size_scale_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position”:”center center”,”_mask_position_tablet”:””,”_mask_position_mobile”:””,”_mask_position_x”:{“unit”:”%”,”size”:0,”sizes”:[]},”_mask_position_x_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position_x_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position_y”:{“unit”:”%”,”size”:0,”sizes”:[]},”_mask_position_y_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position_y_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_repeat”:”no-repeat”,”_mask_repeat_tablet”:””,”_mask_repeat_mobile”:””,”hide_desktop”:””,”hide_tablet”:””,”hide_mobile”:””,”_attributes”:””,”custom_css”:””},”defaultEditSettings”:{“defaultEditRoute”:”content”},”interactions”:{},”elements”:[],”widgetType”:”divider”,”htmlCache”:”\t\t<div class=\”elementor-widget-container\”>\n\t\t\t\t\t\t\t<div class=\”elementor-divider\”>\n\t\t\t<span class=\”elementor-divider-separator\”>\n\t\t\t\t\t\t</span>\n\t\t</div>\n\t\t\t\t\t\t</div>\n\t\t”,”editSettings”:{“defaultEditRoute”:”content”}},{“id”:”c735dd4″,”elType”:”widget”,”isInner”:false,”isLocked”:false,”settings”:{“editor”:”<p>When arranging your own survey, always ensure the professional is <strong>RICS-qualified</strong>. There’s no single surveyor we recommend, as our clients buy across the UK. Instead:</p><ul><li>Search for RICS-accredited firms in your area: <span style=\”color: #0000ff;\”><strong><a style=\”color: #0000ff;\” href=\”https://www.ricsfirms.com/\”>www.ricsfirms.com</a></strong></span></li><li>Compare quotes, reviews, and timescales.</li><li>Choose someone you feel comfortable with.</li></ul>”,”text_color”:”#231F20″,”drop_cap”:””,”text_columns”:””,”text_columns_tablet”:””,”text_columns_mobile”:””,”column_gap”:{“unit”:”px”,”size”:””,”sizes”:[]},”column_gap_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”column_gap_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”align”:””,”align_tablet”:””,”align_mobile”:””,”typography_typography”:””,”typography_font_family”:””,”typography_font_size”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_font_size_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_font_size_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_font_weight”:””,”typography_text_transform”:””,”typography_font_style”:””,”typography_text_decoration”:””,”typography_line_height”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_line_height_tablet”:{“unit”:”em”,”size”:””,”sizes”:[]},”typography_line_height_mobile”:{“unit”:”em”,”size”:””,”sizes”:[]},”typography_letter_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_letter_spacing_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_letter_spacing_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_word_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”typography_word_spacing_tablet”:{“unit”:”em”,”size”:””,”sizes”:[]},”typography_word_spacing_mobile”:{“unit”:”em”,”size”:””,”sizes”:[]},”text_shadow_text_shadow_type”:””,”text_shadow_text_shadow”:{“horizontal”:0,”vertical”:0,”blur”:10,”color”:”rgba(0,0,0,0.3)”},”paragraph_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”paragraph_spacing_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”paragraph_spacing_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”link_color”:””,”link_hover_color”:””,”link_hover_color_transition_duration”:{“unit”:”s”,”size”:””,”sizes”:[]},”drop_cap_view”:”default”,”drop_cap_primary_color”:””,”drop_cap_secondary_color”:””,”drop_cap_shadow_text_shadow_type”:””,”drop_cap_shadow_text_shadow”:{“horizontal”:0,”vertical”:0,”blur”:10,”color”:”rgba(0,0,0,0.3)”},”drop_cap_size”:{“unit”:”px”,”size”:5,”sizes”:[]},”drop_cap_space”:{“unit”:”px”,”size”:10,”sizes”:[]},”drop_cap_border_radius”:{“unit”:”%”,”size”:””,”sizes”:[]},”drop_cap_border_width”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”drop_cap_typography_typography”:””,”drop_cap_typography_font_family”:””,”drop_cap_typography_font_size”:{“unit”:”px”,”size”:””,”sizes”:[]},”drop_cap_typography_font_size_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”drop_cap_typography_font_size_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”drop_cap_typography_font_weight”:””,”drop_cap_typography_text_transform”:””,”drop_cap_typography_font_style”:””,”drop_cap_typography_text_decoration”:””,”drop_cap_typography_line_height”:{“unit”:”px”,”size”:””,”sizes”:[]},”drop_cap_typography_line_height_tablet”:{“unit”:”em”,”size”:””,”sizes”:[]},”drop_cap_typography_line_height_mobile”:{“unit”:”em”,”size”:””,”sizes”:[]},”drop_cap_typography_word_spacing”:{“unit”:”px”,”size”:””,”sizes”:[]},”drop_cap_typography_word_spacing_tablet”:{“unit”:”em”,”size”:””,”sizes”:[]},”drop_cap_typography_word_spacing_mobile”:{“unit”:”em”,”size”:””,”sizes”:[]},”_title”:””,”_margin”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_margin_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_margin_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_padding”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_padding_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_padding_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_element_width”:””,”_element_width_tablet”:””,”_element_width_mobile”:””,”_element_custom_width”:{“unit”:”%”,”size”:””,”sizes”:[]},”_element_custom_width_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_element_custom_width_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_grid_column”:””,”_grid_column_tablet”:””,”_grid_column_mobile”:””,”_grid_column_custom”:””,”_grid_column_custom_tablet”:””,”_grid_column_custom_mobile”:””,”_grid_row”:””,”_grid_row_tablet”:””,”_grid_row_mobile”:””,”_grid_row_custom”:””,”_grid_row_custom_tablet”:””,”_grid_row_custom_mobile”:””,”_flex_align_self”:””,”_flex_align_self_tablet”:””,”_flex_align_self_mobile”:””,”_flex_order”:””,”_flex_order_tablet”:””,”_flex_order_mobile”:””,”_flex_order_custom”:””,”_flex_order_custom_tablet”:””,”_flex_order_custom_mobile”:””,”_flex_size”:””,”_flex_size_tablet”:””,”_flex_size_mobile”:””,”_flex_grow”:1,”_flex_grow_tablet”:””,”_flex_grow_mobile”:””,”_flex_shrink”:1,”_flex_shrink_tablet”:””,”_flex_shrink_mobile”:””,”_element_vertical_align”:””,”_element_vertical_align_tablet”:””,”_element_vertical_align_mobile”:””,”_position”:””,”_offset_orientation_h”:”start”,”_offset_x”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_x_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_x_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_x_end”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_x_end_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_x_end_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_orientation_v”:”start”,”_offset_y”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_y_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_y_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_y_end”:{“unit”:”px”,”size”:0,”sizes”:[]},”_offset_y_end_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_offset_y_end_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_z_index”:””,”_z_index_tablet”:””,”_z_index_mobile”:””,”_element_id”:””,”_css_classes”:””,”e_display_conditions”:””,”_element_cache”:””,”motion_fx_motion_fx_scrolling”:””,”motion_fx_translateY_effect”:””,”motion_fx_translateY_direction”:””,”motion_fx_translateY_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”motion_fx_translateY_affectedRange”:{“unit”:”%”,”size”:””,”sizes”:{“start”:0,”end”:100}},”motion_fx_translateX_effect”:””,”motion_fx_translateX_direction”:””,”motion_fx_translateX_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”motion_fx_translateX_affectedRange”:{“unit”:”%”,”size”:””,”sizes”:{“start”:0,”end”:100}},”motion_fx_opacity_effect”:””,”motion_fx_opacity_direction”:”out-in”,”motion_fx_opacity_level”:{“unit”:”px”,”size”:10,”sizes”:[]},”motion_fx_opacity_range”:{“unit”:”%”,”size”:””,”sizes”:{“start”:20,”end”:80}},”motion_fx_blur_effect”:””,”motion_fx_blur_direction”:”out-in”,”motion_fx_blur_level”:{“unit”:”px”,”size”:7,”sizes”:[]},”motion_fx_blur_range”:{“unit”:”%”,”size”:””,”sizes”:{“start”:20,”end”:80}},”motion_fx_rotateZ_effect”:””,”motion_fx_rotateZ_direction”:””,”motion_fx_rotateZ_speed”:{“unit”:”px”,”size”:1,”sizes”:[]},”motion_fx_rotateZ_affectedRange”:{“unit”:”%”,”size”:””,”sizes”:{“start”:0,”end”:100}},”motion_fx_scale_effect”:””,”motion_fx_scale_direction”:”out-in”,”motion_fx_scale_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”motion_fx_scale_range”:{“unit”:”%”,”size”:””,”sizes”:{“start”:20,”end”:80}},”motion_fx_transform_origin_x”:”center”,”motion_fx_transform_origin_y”:”center”,”motion_fx_devices”:[“desktop”,”tablet”,”mobile”],”motion_fx_range”:””,”motion_fx_motion_fx_mouse”:””,”motion_fx_mouseTrack_effect”:””,”motion_fx_mouseTrack_direction”:””,”motion_fx_mouseTrack_speed”:{“unit”:”px”,”size”:1,”sizes”:[]},”motion_fx_tilt_effect”:””,”motion_fx_tilt_direction”:””,”motion_fx_tilt_speed”:{“unit”:”px”,”size”:4,”sizes”:[]},”handle_motion_fx_asset_loading”:””,”sticky”:””,”sticky_on”:[“desktop”,”tablet”,”mobile”],”sticky_offset”:0,”sticky_offset_tablet”:””,”sticky_offset_mobile”:””,”sticky_effects_offset”:0,”sticky_effects_offset_tablet”:””,”sticky_effects_offset_mobile”:””,”sticky_anchor_link_offset”:0,”sticky_anchor_link_offset_tablet”:””,”sticky_anchor_link_offset_mobile”:””,”sticky_parent”:””,”_animation”:””,”_animation_tablet”:””,”_animation_mobile”:””,”animation_duration”:””,”_animation_delay”:””,”_transform_rotate_popover”:””,”_transform_rotateZ_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotate_3d”:””,”_transform_rotateX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_perspective_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translate_popover”:””,”_transform_translateX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_popover”:””,”_transform_keep_proportions”:”yes”,”_transform_scale_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skew_popover”:””,”_transform_skewX_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewX_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewX_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewY_effect_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_flipX_effect”:””,”_transform_flipY_effect”:””,”_transform_rotate_popover_hover”:””,”_transform_rotateZ_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateZ_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotate_3d_hover”:””,”_transform_rotateX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateX_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_rotateY_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_perspective_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_perspective_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translate_popover_hover”:””,”_transform_translateX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateX_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_translateY_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_popover_hover”:””,”_transform_keep_proportions_hover”:”yes”,”_transform_scale_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scale_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleX_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_hover_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_scaleY_effect_hover_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skew_popover_hover”:””,”_transform_skewX_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewX_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewX_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”_transform_skewY_effect_hover_tablet”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_skewY_effect_hover_mobile”:{“unit”:”deg”,”size”:””,”sizes”:[]},”_transform_flipX_effect_hover”:””,”_transform_flipY_effect_hover”:””,”_transform_transition_hover”:{“unit”:”px”,”size”:””,”sizes”:[]},”motion_fx_transform_x_anchor_point”:””,”motion_fx_transform_x_anchor_point_tablet”:””,”motion_fx_transform_x_anchor_point_mobile”:””,”motion_fx_transform_y_anchor_point”:””,”motion_fx_transform_y_anchor_point_tablet”:””,”motion_fx_transform_y_anchor_point_mobile”:””,”_background_background”:””,”_background_color”:””,”_background_color_stop”:{“unit”:”%”,”size”:0,”sizes”:[]},”_background_color_stop_tablet”:{“unit”:”%”},”_background_color_stop_mobile”:{“unit”:”%”},”_background_color_b”:”#f2295b”,”_background_color_b_stop”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_color_b_stop_tablet”:{“unit”:”%”},”_background_color_b_stop_mobile”:{“unit”:”%”},”_background_gradient_type”:”linear”,”_background_gradient_angle”:{“unit”:”deg”,”size”:180,”sizes”:[]},”_background_gradient_angle_tablet”:{“unit”:”deg”},”_background_gradient_angle_mobile”:{“unit”:”deg”},”_background_gradient_position”:”center center”,”_background_gradient_position_tablet”:””,”_background_gradient_position_mobile”:””,”_background_image”:{“url”:””,”id”:””,”size”:””},”_background_image_tablet”:{“url”:””,”id”:””,”size”:””},”_background_image_mobile”:{“url”:””,”id”:””,”size”:””},”_background_position”:””,”_background_position_tablet”:””,”_background_position_mobile”:””,”_background_xpos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_xpos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_xpos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_ypos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_ypos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_ypos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_attachment”:””,”_background_repeat”:””,”_background_repeat_tablet”:””,”_background_repeat_mobile”:””,”_background_size”:””,”_background_size_tablet”:””,”_background_size_mobile”:””,”_background_bg_width”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_bg_width_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_bg_width_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_video_link”:””,”_background_video_start”:””,”_background_video_end”:””,”_background_play_once”:””,”_background_play_on_mobile”:””,”_background_privacy_mode”:””,”_background_video_fallback”:{“url”:””,”id”:””,”size”:””},”_background_slideshow_gallery”:[],”_background_slideshow_loop”:”yes”,”_background_slideshow_slide_duration”:5000,”_background_slideshow_slide_transition”:”fade”,”_background_slideshow_transition_duration”:500,”_background_slideshow_background_size”:””,”_background_slideshow_background_size_tablet”:””,”_background_slideshow_background_size_mobile”:””,”_background_slideshow_background_position”:””,”_background_slideshow_background_position_tablet”:””,”_background_slideshow_background_position_mobile”:””,”_background_slideshow_lazyload”:””,”_background_slideshow_ken_burns”:””,”_background_slideshow_ken_burns_zoom_direction”:”in”,”_background_hover_background”:””,”_background_hover_color”:””,”_background_hover_color_stop”:{“unit”:”%”,”size”:0,”sizes”:[]},”_background_hover_color_stop_tablet”:{“unit”:”%”},”_background_hover_color_stop_mobile”:{“unit”:”%”},”_background_hover_color_b”:”#f2295b”,”_background_hover_color_b_stop”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_hover_color_b_stop_tablet”:{“unit”:”%”},”_background_hover_color_b_stop_mobile”:{“unit”:”%”},”_background_hover_gradient_type”:”linear”,”_background_hover_gradient_angle”:{“unit”:”deg”,”size”:180,”sizes”:[]},”_background_hover_gradient_angle_tablet”:{“unit”:”deg”},”_background_hover_gradient_angle_mobile”:{“unit”:”deg”},”_background_hover_gradient_position”:”center center”,”_background_hover_gradient_position_tablet”:””,”_background_hover_gradient_position_mobile”:””,”_background_hover_image”:{“url”:””,”id”:””,”size”:””},”_background_hover_image_tablet”:{“url”:””,”id”:””,”size”:””},”_background_hover_image_mobile”:{“url”:””,”id”:””,”size”:””},”_background_hover_position”:””,”_background_hover_position_tablet”:””,”_background_hover_position_mobile”:””,”_background_hover_xpos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_xpos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_xpos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_ypos”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_ypos_tablet”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_ypos_mobile”:{“unit”:”px”,”size”:0,”sizes”:[]},”_background_hover_attachment”:””,”_background_hover_repeat”:””,”_background_hover_repeat_tablet”:””,”_background_hover_repeat_mobile”:””,”_background_hover_size”:””,”_background_hover_size_tablet”:””,”_background_hover_size_mobile”:””,”_background_hover_bg_width”:{“unit”:”%”,”size”:100,”sizes”:[]},”_background_hover_bg_width_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_hover_bg_width_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_background_hover_video_link”:””,”_background_hover_video_start”:””,”_background_hover_video_end”:””,”_background_hover_play_once”:””,”_background_hover_play_on_mobile”:””,”_background_hover_privacy_mode”:””,”_background_hover_video_fallback”:{“url”:””,”id”:””,”size”:””},”_background_hover_slideshow_gallery”:[],”_background_hover_slideshow_loop”:”yes”,”_background_hover_slideshow_slide_duration”:5000,”_background_hover_slideshow_slide_transition”:”fade”,”_background_hover_slideshow_transition_duration”:500,”_background_hover_slideshow_background_size”:””,”_background_hover_slideshow_background_size_tablet”:””,”_background_hover_slideshow_background_size_mobile”:””,”_background_hover_slideshow_background_position”:””,”_background_hover_slideshow_background_position_tablet”:””,”_background_hover_slideshow_background_position_mobile”:””,”_background_hover_slideshow_lazyload”:””,”_background_hover_slideshow_ken_burns”:””,”_background_hover_slideshow_ken_burns_zoom_direction”:”in”,”_background_hover_transition”:{“unit”:”px”,”size”:””,”sizes”:[]},”_border_border”:””,”_border_width”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_width_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_width_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_color”:””,”_border_radius”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_box_shadow_box_shadow_type”:””,”_box_shadow_box_shadow”:{“horizontal”:0,”vertical”:0,”blur”:10,”spread”:0,”color”:”rgba(0,0,0,0.5)”},”_box_shadow_box_shadow_position”:” “,”_border_hover_border”:””,”_border_hover_width”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_hover_width_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_hover_width_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_hover_color”:””,”_border_radius_hover”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_hover_tablet”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_border_radius_hover_mobile”:{“unit”:”px”,”top”:””,”right”:””,”bottom”:””,”left”:””,”isLinked”:true},”_box_shadow_hover_box_shadow_type”:””,”_box_shadow_hover_box_shadow”:{“horizontal”:0,”vertical”:0,”blur”:10,”spread”:0,”color”:”rgba(0,0,0,0.5)”},”_box_shadow_hover_box_shadow_position”:” “,”_border_hover_transition”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_switch”:””,”_mask_shape”:”circle”,”_mask_image”:{“url”:””,”id”:””,”size”:””},”_mask_image_tablet”:{“url”:””,”id”:””,”size”:””},”_mask_image_mobile”:{“url”:””,”id”:””,”size”:””},”_mask_size”:”contain”,”_mask_size_tablet”:””,”_mask_size_mobile”:””,”_mask_size_scale”:{“unit”:”%”,”size”:100,”sizes”:[]},”_mask_size_scale_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_size_scale_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position”:”center center”,”_mask_position_tablet”:””,”_mask_position_mobile”:””,”_mask_position_x”:{“unit”:”%”,”size”:0,”sizes”:[]},”_mask_position_x_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position_x_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position_y”:{“unit”:”%”,”size”:0,”sizes”:[]},”_mask_position_y_tablet”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_position_y_mobile”:{“unit”:”px”,”size”:””,”sizes”:[]},”_mask_repeat”:”no-repeat”,”_mask_repeat_tablet”:””,”_mask_repeat_mobile”:””,”hide_desktop”:””,”hide_tablet”:””,”hide_mobile”:””,”_attributes”:””,”custom_css”:””},”defaultEditSettings”:{“defaultEditRoute”:”content”},”interactions”:{},”elements”:[],”widgetType”:”text-editor”,”htmlCache”:”\t\t<div class=\”elementor-widget-container\”>\n\t\t\t\t\t\t\t\t\t\t<div class=\”elementor-text-editor elementor-clearfix elementor-inline-editing\” data-elementor-setting-key=\”editor\” data-elementor-inline-editing-toolbar=\”advanced\”>\n\t\t\t\t<p>When arranging your own survey, always ensure the professional is <strong>RICS-qualified</strong>. There’s no single surveyor we recommend, as our clients buy across the UK. Instead:</p><ul><li>Search for RICS-accredited firms in your area: <span style=\”color: #0000ff;\”><strong><a style=\”color: #0000ff;\” href=\”https://www.ricsfirms.com/\”>www.ricsfirms.com</a></strong></span></li><li>Compare quotes, reviews, and timescales.</li><li>Choose someone you feel comfortable with.</li></ul>\t\t\t\t\t</div>\n\t\t\t\t\t\t\t\t</div>\n\t\t”,”editSettings”:{“defaultEditRoute”:”content”,”panel”:{“activeTab”:”content”,”activeSection”:”section_editor”}}}]}You can use the findings to renegotiate the price, ask the seller to fix issues, or — if the problems are too significant — decide to walk away.You can use the findings to renegotiate the price, ask the seller to fix issues, or — if the problems are too significant — decide to walk away.You can use the findings to renegotiate the price, ask the seller to fix issues, or — if the problems are too significant — decide to walk away.

Making the Right Call on Surveys

The mortgage valuation protects the lender — but it doesn’t protect you. Commissioning your own survey is about safeguarding your investment and avoiding expensive surprises.

Our advice is simple:

  • Understand the difference between a lender’s valuation and a survey.
  • Time your survey for the middle of the transaction.
  • Choose the right type of survey for your property.
  • For new builds, consider a snagging survey instead.

At Nachu Finance, we’ll guide you through every step of the mortgage journey — including when and how to arrange a survey — so you can move forward with confidence.

Make Every Step Count

A property survey can be the difference between a confident purchase and an expensive mistake. Whether it helps you renegotiate, gives peace of mind, or signals it’s time to walk away, it’s a crucial part of the buying journey.

At Nachu Finance, we don’t just arrange mortgages — we guide you through the wider process, including when and how to commission a survey. Our aim is to make sure you have the right information at the right time, so you can move forward without doubts.

Contact us today to discuss your property purchase — and take your next step with clarity and confidence.
Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.
Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Further Reading Section
Two doors labelled Personal Name and Limited Company

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

Buying a Buy-to-Let Property – Personal Name vs Limited Company Ownership

Two doors labelled Personal Name and Limited Company

A very common question from clients looking to invest in a buy-to-let property is whether it is better to purchase in a personal name or through a limited company.

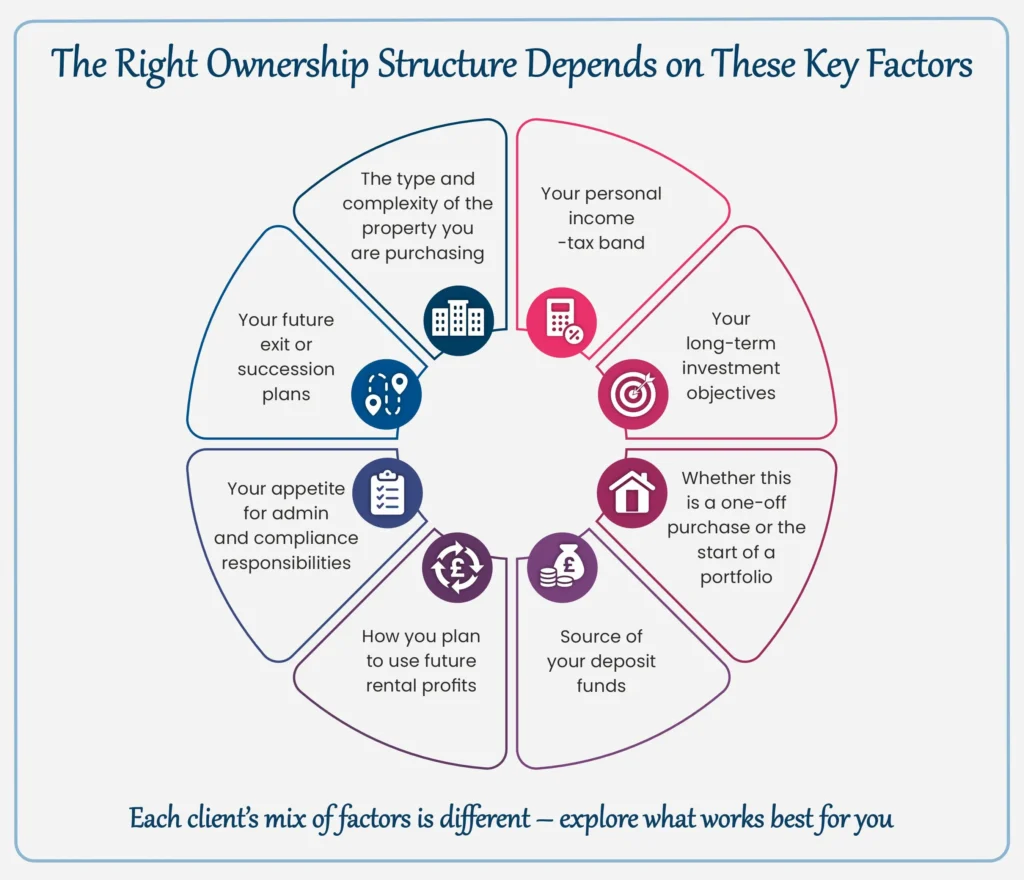
The short answer is: there is no one-size-fits-all solution. The best structure depends on your individual circumstances, tax position, and long-term objectives. In this article, we’ll explore the broad considerations for each route – but before diving into the comparison, there are a couple of important points to clarify.

Before Anything Else – Understand the Responsibilities of Being a Landlord

Owning property as an investment is not the same as investing in stocks, bonds, or commodities. A buy-to-let comes with legal, financial, and moral responsibilities. These include ensuring the property is safe, compliant with regulations, and that tenants are treated fairly.

Before weighing up ownership structures, make sure you fully understand what being a landlord entails. Otherwise, you risk facing unwelcome surprises after completing your purchase.

👉 We’ve written a detailed article on this topic: The Realities of Buy-to-Let – What Every Landlord Needs to Know.

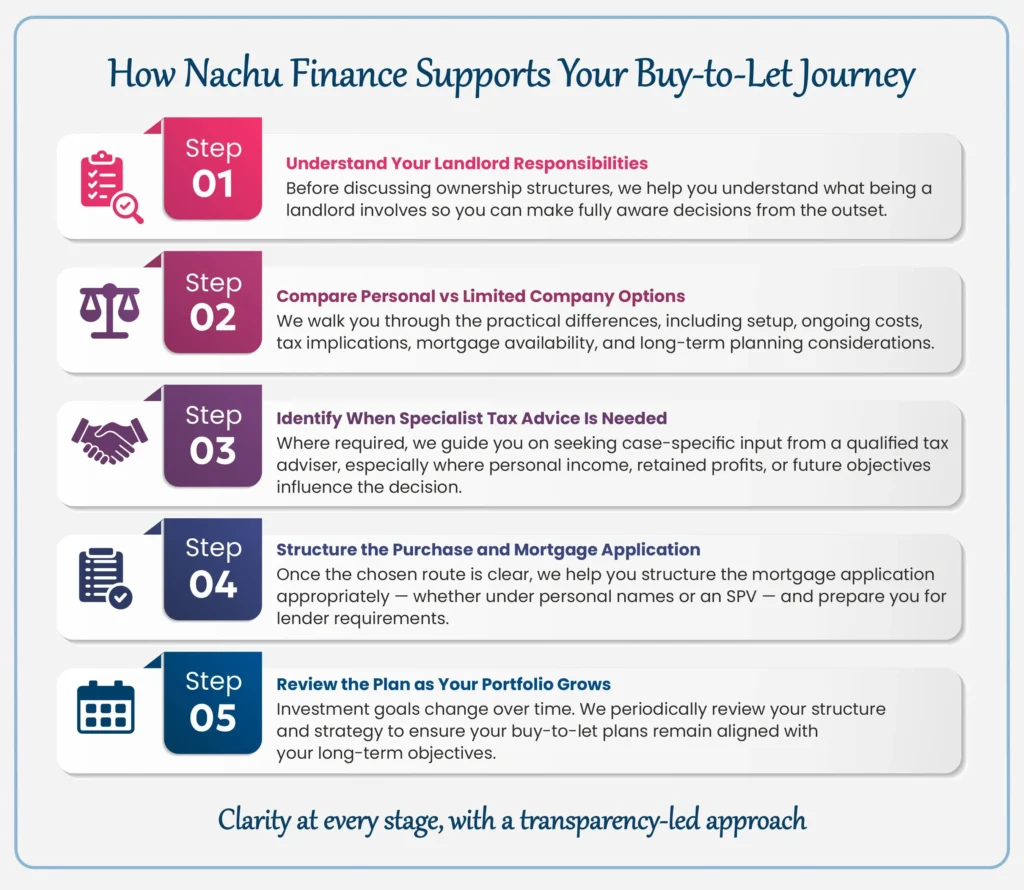
Personal Name Ownership – The Simpler Option

Buying a buy-to-let in your personal name is generally:

  • Simpler to set up and manage – no need to create and maintain a company structure.
  • Lower cost – ongoing compliance, accounting, and administration are minimal compared with a company.
  • Access to cheaper mortgage rates – lenders usually offer more competitive rates for personally owned properties.

The downside: personal ownership is often less tax efficient. Rental profits are taxed at your marginal income tax rate, and high earners can feel the impact of reduced mortgage interest tax relief.


Limited Company Ownership – The Tax-Efficient Route

Using a limited company (commonly set up as a Special Purpose Vehicle or “SPV”) has its advantages:

  • Tax efficiency – profits are subject to corporation tax, which may be more favourable depending on your income bracket.
  • Flexibility for reinvestment – easier to reinvest profits into future property purchases without incurring personal tax first.
  • Long-term planning – can allow for more efficient inheritance and capital gains planning.

The trade-offs include:

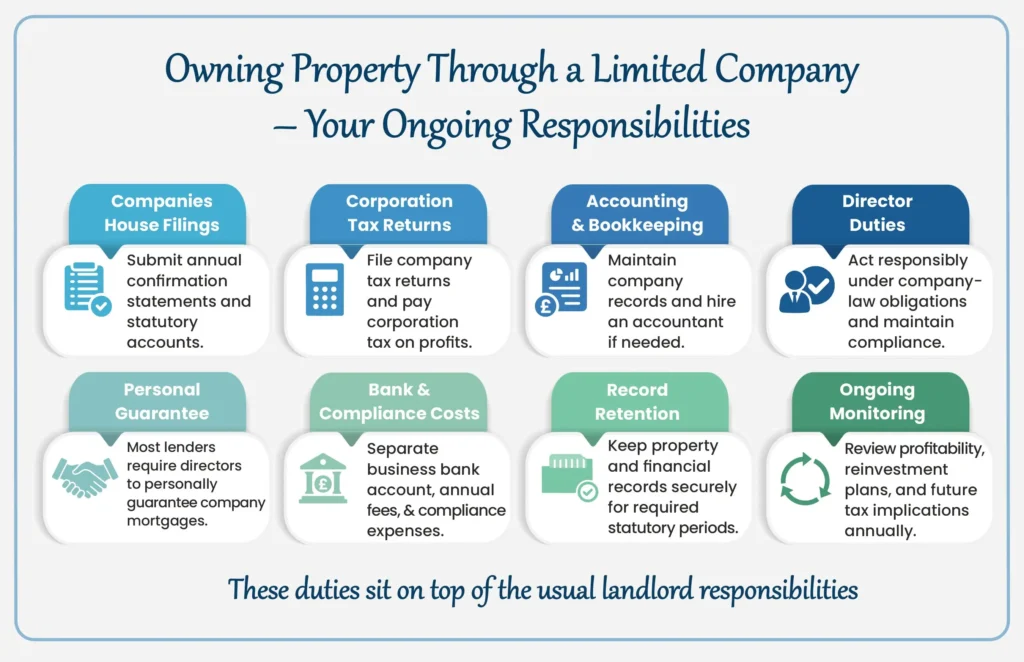
  • Setup and running costs – accountancy fees, compliance charges, bank fees, and Companies House filing obligations.
  • Mortgage considerations – limited company mortgage rates are usually higher than personal ones.
  • Director responsibilities – you will need to act as a director and comply with company law.
  • Personal guarantees – lenders typically require directors to give personal guarantees when borrowing through a limited company.

At a Glance – How Personal Name and Limited Company Ownership Compare

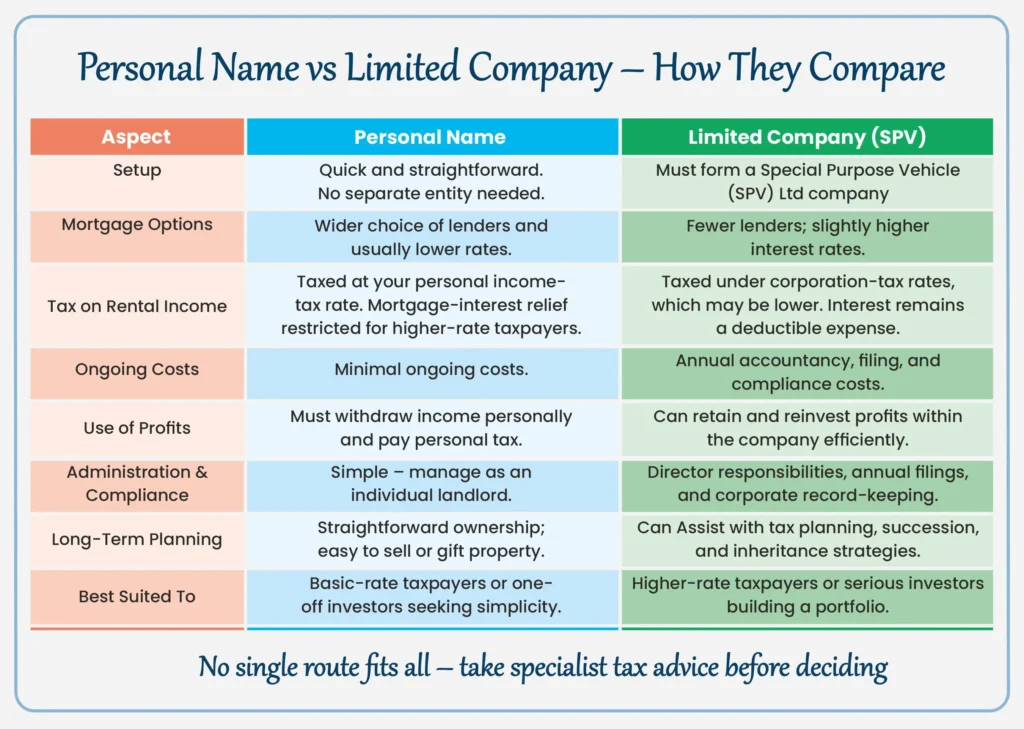
To help summarise the key differences, the infographic below provides a quick visual comparison of both routes.

Table comparing personal name and limited company buy-to-let ownership

Important Distinction – Buying New vs Transferring Existing

This article focuses on the decision when purchasing a new buy-to-let property.

Transferring an existing personally owned property into a limited company is a separate subject. Such transfers often trigger stamp duty and capital gains tax, and can be expensive unless there is a strong reason.

👉 For more detail on this specific scenario, see: Transferring Property into a Limited Company.

When Might a Personal Name Make More Sense?

  • You are a basic rate taxpayer or have no other income.
  • You are buying a one-off buy-to-let rather than building a portfolio.
  • You want a simpler, lower-cost route with less paperwork and compliance.
  • You prefer access to lower mortgage interest rates.

When Might a Limited Company Make More Sense?

  • You are a higher rate or additional rate taxpayer.
  • You already run a trading limited company and have significant retained profits you wish to reinvest.
  • You are building a portfolio of buy-to-lets and plan to treat property as a serious long-term business.
  • You want more flexibility for tax planning and inheritance planning.

Additional responsibilities with a limited company include:

Below is a summary of the additional responsibilities landlords must meet when using a limited company structure.

  • Annual filings with Companies House (confirmation statements, statutory accounts).
  • Corporation tax returns and ongoing accountancy costs.
  • Acting as a director/shareholder and ensuring compliance with company law.

Personal guarantees: even if the mortgage is in the limited company’s name, most lenders will require the directors to personally guarantee the loan. This means that if the company defaults, your personal assets may still be at risk.

Long-Term Objectives and Exit Strategy

Your end goal should influence the decision. For example:

  • If you plan to sell the property and cash out the gains, your tax route may look different in personal names versus a company.
  • If your plan is to retain and pass on the property, limited companies can sometimes help with inheritance planning and structuring shares.
  • If your plan is simply to earn rental income during retirement, personal names may be simpler and more cost-effective.

Choosing the right structure depends on a combination of factors. The infographic below outlines the key elements that typically influence what works best for each client

Circular diagram of factors influencing the choice of ownership structure

Real-Life Case Studies

The decision between purchasing a buy-to-let property in personal names or through a limited company depends heavily on each client’s individual circumstances.
Below are two real examples that highlight how different factors can lead to entirely different ownership structures, yet both outcomes were appropriate and efficient for the clients involved.

Balaji is a full-time NHS doctor and a higher-rate taxpayer. Nila is a homemaker with no personal income, and her long-term plan is to continue in this role. The couple received an inheritance from Nila’s parents and wanted to invest part of it into a single buy-to-let property located close to their main home. Their intention was simply to hold one additional property for future family needs, rather than building a wider portfolio or running a property business.

Given their objectives, their tax positions and the source of deposit, the couple sought tax advice and considered both ownership routes.
The outcome was clear: purchasing in personal names suited their circumstances best.

To reflect the origin of the deposit and to ensure the rental income was taxed more efficiently, they chose to own the property as tenants in common with unequal shares — 90 percent for Nila and 10 percent for Balaji.

This structure aligned with their financial objectives, long-term plans and family considerations.

For readers who wish to understand the difference between joint tenancy and tenants in common, we have explained this in detail here:
https://nachufinance.co.uk/joint-tenancy-vs-tenants-in-common/

Sai and Devi are married, both higher-rate taxpayers and both expecting to remain in well-paid full-time roles. Sai is an IT contractor operating through his own trading limited company, which had accumulated around £140,000 in retained profits. Their long-term aim was to build a small property portfolio over the years.

Because they were already higher-rate taxpayers and the deposit was coming from retained profits within a trading company, purchasing in personal names would have meant drawing funds as dividends and incurring additional personal tax.

After discussing their situation with their accountant and taking specialist tax advice, they decided that purchasing through a new limited company (SPV) was the more efficient and future-proof structure.
This allowed them to deploy the retained profits more effectively and positioned them better for expanding their property portfolio over time.

The two examples above demonstrate situations where one structure clearly made more sense than the other.
However, in many real-life scenarios, clients present a mix of factors — some favouring personal ownership and others favouring a limited-company route.

In such cases, the decision is not straightforward.
It often requires weighing up long-term objectives, tax considerations, deposit sources, income levels, portfolio intentions and administrative responsibilities before arriving at an informed and balanced choice.

Every client’s circumstances are different, and the most suitable structure is the one that aligns with their overall financial picture and future plans.

Our Transparency Promise

Multiple Professionals Are Involved in Getting This Right

Choosing whether to hold a buy-to-let property in your personal name or through a limited company is not a decision made in isolation.
Before finalising your route, you will usually need input from more than one professional:

  • A mortgage adviser to explain lending rules, interest-rate differences, and structuring requirements.
  • A qualified tax adviser to confirm how each option affects your personal tax position, long-term plans, and future liabilities.

While we can guide you on how each structure works from a property-finance perspective, we are not tax advisers, and tax planning sits outside the scope of mortgage advice.
Given the long-term consequences of choosing the wrong structure, we strongly recommend seeking independent, specialist tax advice before arriving at a final decision.

For more details on why specialist advice is crucial in these scenarios, see our article on
Specialist Property Tax Advice: https://nachufinance.co.uk/tag/specialist-property-tax-advice/

Our goal is to ensure you make a well-informed decision, and that all relevant professionals are involved where needed.

How Nachu Finance Supports Your Buy-to-Let Journey

Five-step process for planning a buy-to-let, from landlord duties to review

At Nachu Finance, our role is to guide you through every stage of your buy-to-let planning with clarity and structure.

We start by ensuring you fully understand what it means to be a landlord, then help you compare the practical differences between personal ownership and using a limited company.

Where a tax specialist’s input is needed, we point you in the right direction so your decision is made with complete confidence.
Once the structure is clear, we help you position the mortgage application correctly and follow through with the paperwork, lender requirements and timelines. As your plans evolve, we continue to review your approach so your strategy remains aligned with your long-term goals.

Ready to Explore Which Structure Works Best for You?

At Nachu Finance, we understand that buying an investment property is a long-term commitment, and getting the structure right at the outset can make a meaningful difference over time. We are always happy to have an initial conversation, understand your goals and personal circumstances, and outline the available options in a clear and transparent way.

Where required, we can also refer you to experienced tax specialists so you receive the right guidance from all relevant professionals.

If you are planning a purchase, weighing up your options, or would simply like to talk through the considerations, feel free to reach out. We will be glad to guide you and support you at every stage.

Frequently Asked Questions

No, not all lenders offer mortgages to limited companies. However, more and more lenders—including well-known high-street names such as Birmingham Midshires, Coventry Building Society and The Mortgage Works—are now active in this space.
It is fair to say the choice is still more limited compared with personal-name mortgages, but as limited-company structures become more popular with landlords, the number of lenders willing to lend to SPVs continues to grow.
Criteria and flexibility vary significantly between lenders, so understanding who supports what structure is important before finalising your route.

Generally speaking, yes.
Limited-company mortgage rates tend to be slightly higher than equivalent products in personal names.
However, the interest rate should not be looked at in isolation.
A limited company can offer potential tax advantages and reinvestment benefits which, depending on your circumstances, may outweigh the slightly higher cost of borrowing.
The decision should therefore be based on the overall position and long-term outcomes, not the rate alone.

Yes, you can.
The limited company simply acts as the legal “envelope” for the mortgage. All due diligence—identity checks, credit checks, income verification, deposit evidence and background assessments—is still performed on you as the applicants.
Because of this, lenders are generally comfortable with:

  • a newly incorporated SPV, or
  • a company that will be set up shortly before the mortgage application is submitted.

A new company is not a negative point and does not reduce your chances of obtaining a mortgage.

In most cases, yes.
Although the property is owned by the limited company, lenders usually require all directors and shareholders to provide a personal guarantee.
This means you remain personally responsible if the limited company fails to meet the mortgage obligations.
Additionally, lenders often require you to take independent legal advice before signing the personal-guarantee documents, because the guarantee creates obligations separate from the company.

Often yes, but the way you structure this makes a significant difference.
If the property is purchased in your personal name, you would first need to withdraw the funds from the trading company and pay any tax due on the withdrawal (for example, dividend tax). Only then can the funds be used as your personal deposit.
However, if the property is purchased through a limited company SPV, there may be more efficient options, such as:

  • inter-company loans, or
  • structuring the SPV as a subsidiary of your trading company.

These options can avoid unnecessary tax leakage and allow efficient use of retained profits. Because the tax implications vary widely, this is an area where specialist tax advice is strongly recommended.

Generally speaking, no. Only a small number of lenders accept gifted deposits under a limited-company structure

Most lenders do not permit gifted deposits when buying through a limited company.
Gifted deposits are far more commonly accepted for:

  • residential property purchases, and
  • buy-to-let purchases in personal names.

If using a gifted deposit forms part of your plan, it is essential to confirm lender acceptance before progressing too far.

In theory, yes — but in practice, most lenders prefer not to lend to active trading companies.
Only a handful of lenders will consider a mortgage where the borrowing entity is a trading business, and the choice of products is very limited.
Setting up a separate Special Purpose Vehicle (SPV) specifically for property investment generally:

  • keeps borrowing cleaner,
  • simplifies lender due diligence,
  • avoids mixing trading activity with property assets, and
  • ensures a wider choice of lenders and mortgage products.

Yes, it is possible and you should consider.
Whether you are a first-time landlord or an experienced investor, the considerations remain the same:

  • your tax position,
  • your long-term investment plans,
  • the source of your deposit,
  • your comfort with administrative responsibility, and
  • whether you intend to build a portfolio.

Being a first-time landlord does not restrict you from using a limited company; it simply means the need to understand both options clearly is even more important.

In many cases, yes.
Some lenders do allow both adult and minor children to hold shares in a property SPV.
However, every lender applies its own criteria regarding:

  • acceptable ages,
  • maximum shareholding percentages, and
  • any responsibilities or limitations placed on younger shareholders.

If involving your children forms part of your long-term strategy, this should be discussed at the outset so that a suitable lender can be identified.

A limited company, on its own, is not an inheritance-tax or succession-planning solution.
While shareholding allows some flexibility in how interests are held or transferred, this does not automatically reduce inheritance tax or solve estate-planning needs.

Inheritance Tax planning is a separate and specialist area, and decisions about property ownership should be reviewed together to get the full picture.

If you buy a buy-to-let in your personal name, then when you go on to buy your residential property, it will be treated as an additional property, and the 5% additional stamp duty will apply. You will not be considered a first-time buyer.
If you buy the buy-to-let through a limited company, your personal first-time buyer status is not affected, provided you do not personally own any property.

Yes.
Regardless of whether this is the company’s first property or whether the company has only just been formed, the 5% additional stamp duty surcharge automatically applies to all limited-company residential property purchases.

In practice, no.
The tax rules — including ATED (Annual Tax on Enveloped Dwellings) — and higher stamp duty make it uneconomical for an individual to buy their own home through a limited company.

In addition, mortgage lenders do not offer residential mortgages to limited companies for owner-occupied properties.
For these reasons, a limited-company structure is used only for buy-to-let properties, not residential homes for personal occupation.

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.
Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Continue the Best Practices of Family Protection
Tax Year Overview and SA302 documents used to verify income for a UK mortgage application
Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

Tax Year Overview: What It Is, Why It Matters for Your Mortgage, and How to Download It

Tax Year Overview and SA302 documents used to verify income for a UK mortgage application
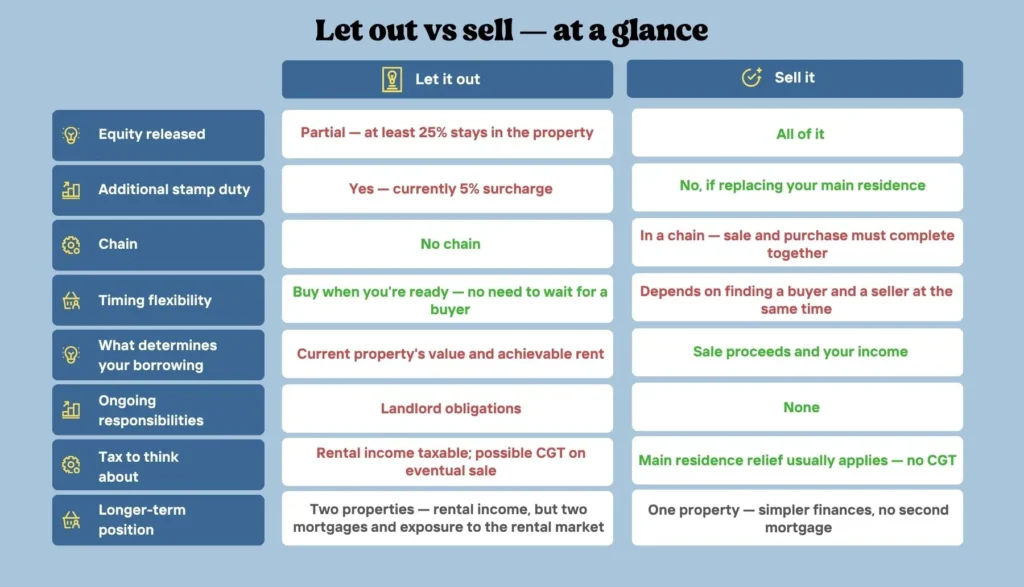
When applying for a mortgage, especially as a self-employed individual or landlord, one document that often causes confusion is the Tax Year Overview (TYO). Many clients aren’t aware of what this document is, how it differs from the tax calculation, or how to download it correctly from the HMRC website.
Let’s clear up the confusion and walk you through what a Tax Year Overview is, when it’s required, and how to avoid common mistakes when submitting it.

What Is a Tax Year Overview?

A Tax Year Overview is a one-page document issued by HMRC confirming your income tax position for a specific tax year. It shows:

  • The amount of tax due
  • The payments made towards that tax
  • Any interest, penalties, or surcharges
  • Whether the tax has been fully paid as of the download date

This is not the same as a Tax Calculation (previously known as the SA302), which shows how HMRC calculated your income and tax owed based on your Self Assessment. Lenders typically require both documents to cross-verify the income and payment details.

When Is It Required?

This document is typically required by mortgage lenders to verify income for applicants who:

  • Are self-employed and submit Self-Assessment tax returns (this includes sole traders, partners, and Ltd company directors or shareholders)
  • Receive rental income under the “income from land and property” heading

In these cases, the TYO must match exactly with the figures shown in the corresponding tax calculation (SA302).

Why Lenders Need It

Lenders use the Tax Year Overview to cross-check the income tax amount declared in the tax calculation. If the two documents don’t match to the penny, they will be rejected, potentially delaying your mortgage application.

How to Get Your Tax Year Overview

You have three options to obtain your TYO:

  1. From Your Accountant – Your accountant can usually provide this quickly.
  2. Call HMRC – You can request HMRC to post it, but this takes time and isn’t ideal for future use.
  3. Download Directly from HMRC Online – Recommended for speed and ongoing access.

Steps to Download from HMRC Website

  1. Go to: https://www.gov.uk/log-in-register-hmrc-online-services
  2. Log in or register
  3. Select ‘Self Assessment’
  4. Under ‘Previously Filed Returns’, click ‘View your tax year overview’
  5. Select the relevant tax year and click ‘Go’
  6. Click ‘Print your tax year overview’ and choose ‘Save as PDF’
  7. Save the document and share it as needed

Common Mistakes to Avoid

  1. Not refreshing the page by clicking ‘Go’ after selecting the year
  2. Providing mismatched years between tax calculation and TYO
  3. Submitting TYOs that show unpaid taxes or interest
  4. Differences in figures between TYO and tax calculation

How Recent Should the Tax Year Overview Be?

While HMRC allows you to submit your Self Assessment for the previous tax year ending 5th April by the following 31st January, lenders often expect more up-to-date documents.

HMRC Deadline: For the tax year ending 5th April 2026, HMRC allows submissions until 31st January 2027.

Lender Expectations: Most lenders will only accept income documents that are no more than 18 months old. This means:

  1. If you are applying for a mortgage in December 2026, the tax documents for the year ending 5th April 2025 may already be too old.
  2. Instead, lenders will expect to see documents for the tax year ending 5th April 2026.

If you are planning to apply for a mortgage between October and January, it is advisable to:

  1. Submit your tax return sooner than the HMRC deadline
  2. Ensure that both the Tax Calculation and Tax Year Overview reflect the most recent tax year

This consideration is especially important for self-employed applicants and landlords. Lender expectations during this period may exceed HMRC’s timeline, and being proactive helps prevent unnecessary delays or rejections.

From 6th April 2026, Making Tax Digital for Income Tax applies to sole traders and landlords with qualifying income over £50,000. The threshold falls to £30,000 from April 2027 and £20,000 from April 2028.

Under Making Tax Digital, you keep digital records and send quarterly updates to HMRC using compatible software. After the end of the tax year, you complete and submit your tax return through compatible software. The 31st January tax return and payment deadline continues to apply.

For mortgage applications being made now, the documents lenders ask for still come from the existing Self Assessment process, because 2026/27 is the first tax year under the new system. HMRC has not yet confirmed whether the Tax Calculation or Tax Year Overview will change once Making Tax Digital returns start coming through, and lenders may update their requirements as it beds in.

Quick Checklist for Mortgage-Suitable Tax Documents

Checklist of seven tax document requirements lenders expect from self-employed mortgage applicants
  1. Tax Calculation (SA302) downloaded from HMRC or your accountant
  2. Matching Tax Year Overview for the same year
  3. Figures on both documents match exactly to the penny
  4. Documents cover the most recent 2 tax years
  5. No outstanding payments showing on the Tax Year Overview
  6. Documents are less than 18 months old at the time of application
  7. You’ve pressed ‘Go’ before downloading from HMRC (to refresh the year selected)

Sample Tax Year Overview

Example of an HMRC Tax Year Overview showing tax due, payments made and the remaining balance

Frequently Asked Questions

No, the Tax Year Overview confirms payments made to HMRC, whereas the SA302 shows your income and tax liability as calculated.

No. Lenders typically require both the Tax Calculation and the Tax Year Overview for cross-verification.

Lenders expect the figures on both documents to match, so a mismatch needs resolving before your application goes in. In our experience, this usually happens when the tax return has been amended after the Tax Calculation was produced, leaving you with an earlier version. Ask your accountant for the latest Tax Calculation, which will normally match your Tax Year Overview.

You’ll need to make the payment and re-download the updated Tax Year Overview before it will be accepted by most lenders.

 HMRC advises that you cannot print your Tax Calculation or Tax Year Overview until 72 hours after submitting your tax return. If you are planning a mortgage application, file early enough to allow for this and, where possible, make sure any tax due has been paid so the overview does not show an outstanding balance.

Need Help Getting It Right?

At Nachu Finance, we understand that navigating the mortgage process—especially as a self-employed individual or landlord—can feel complex and overwhelming. That’s why we go beyond simply ticking boxes. We work closely with you to ensure your documents are accurate, up to date, and fully aligned with what lenders expect.

From helping you retrieve the right Tax Year Overview and Tax Calculation, to advising on how to present your income clearly, we’re here to make the process smoother and more transparent. Whether you’re preparing for your first mortgage or a remortgage, our advice is always tailored to your unique situation.

Get in touch today and let us help you submit with confidence

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Strengthen Your Mortgage Application Preparation

House keys passed between two hands, illustrating Capital Gains Tax on gifting property

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

Understanding Capital Gains Tax When Gifting or Inheriting Property

House keys passed between two hands, illustrating Capital Gains Tax on gifting property

Capital Gains Tax (CGT) is payable to HMRC on the gain made when disposing of an asset, including property. However, it’s not just sales that are classed as a disposal—gifting a property can also trigger CGT.

In this article, we explore the implications of gifting a property either fully or partially, how it differs from inherited property, and what happens when property is placed into a trust. We also look at Stamp Duty considerations and share a real-life case study involving a family who transferred property between siblings.

CGT on Property That Is Not Your Main Home

Capital Gains Tax (CGT) in the UK applies to properties that are not used as your primary residence, such as:

  • Buy-to-let properties
  • Second homes
  • Holiday homes

As of 6 April 2025, CGT rates on residential property are:

  • 18% for basic rate taxpayers
  • 24% for higher or additional rate taxpayers

CGT on a Previously Residential Property

If a property has been used as your main home for part of its ownership and rented out for the rest, you may qualify for partial relief. The CGT will be proportionate, with a deduction for the time the property was your primary residence.

Gifting Property to Family – Key Principles

Even though no money changes hands, gifting a property is treated by HMRC as if it were sold at market value. That means CGT is still assessed on the gain.

Example: Gifting a Property to a Child

Let us suppose Grace purchased a buy-to-let property in 2010 for £320,000. In 2025, she decides to gift it to her daughter without taking any payment. If the property is now worth £550,000, then the gain of £230,000 (before costs and allowances) is still subject to CGT.

If Grace chooses to gift only 50% of the property, then CGT will be due on half the gain—£115,000 in this case.

CGT is based on market value at the time of the gift, not the original purchase price or amount received.

Example: Gifting to a Spouse

Let us suppose Harrison bought a buy-to-let property in 2015 for £250,000. In 2025, after marrying Thea, he transfers 50% of the property to her. The property is now worth £400,000.

Ordinarily, this £150,000 gain would make half the gain (£75,000) taxable. However, transfers between spouses or civil partners are exempt from CGT, so no tax is payable here.

Table comparing Capital Gains Tax treatment of gifts to children, spouses, trusts and inheritance

Valuation When Gifting to Family

When property is gifted to a close relative, there’s no actual sale to determine an open-market value. To avoid disputes or challenges from HMRC, we recommend obtaining a formal valuation from a RICS-approved surveyor—that is, a member of the Royal Institution of Chartered Surveyors, the globally recognised professional body for land, property, and construction standards. A RICS valuation provides credible evidence of the property’s market value at the time of the gift and offers stronger protection if ever reviewed by HMRC.

This offers:

  • Credible evidence if HMRC questions the valuation
  • Peace of mind for both parties
  • Stronger protection than using an estate agent or mortgage lender’s estimate

Transferring Property into a Lifetime Trust

When transferring an investment property to a lifetime trust, it’s possible to defer CGT using holdover relief. This does not exempt the tax but postpones it.

Example: Using Holdover Relief

Let us suppose Dinesh and Gayathri bought a buy-to-let in 2000 for £200,000. In 2015, when it was valued at £500,000, they placed it into a Family Holdover Gift Trust, deferring the gain.

In 2025, the trust sells the property for £700,000. CGT is payable on the full gain of £500,000 (from £200,000 to £700,000), because the deferred gain is carried forward.

If they had instead paid the CGT in 2015 on the £300,000 gain, the 2025 sale would only attract tax on the £200,000 increase since then.

Holdover relief defers the CGT—it doesn’t erase it.

👉 You can read more here: Transferring Property to a Lifetime Trust – Full Guide

Capital Gains Tax on Inherited Property

It’s important to understand that Capital Gains Tax (CGT) does not apply when a property is passed on through inheritance. When the owner passes away, any unrealised gains effectively die with them. Instead, Inheritance Tax (IHT) may apply to the estate based on the total value of the deceased’s assets, including the property.

Example: Inheriting vs Gifting During Lifetime

Let us suppose Dinesh and Gayathri owned a buy-to-let property purchased for £200,000 in 2000. In 2025, the property is worth £700,000. If they had not gifted the property during their lifetime (either directly or via a trust) and instead passed it to their son Ashwin via their Will:

  • No CGT would be payable on the £500,000 gain (£700K – £200K)
  • The property would be revalued to £700,000 as part of probate
  • IHT may be payable on the £700,000, depending on the size of the estate
  • When Ashwin eventually sells the property, his base cost for CGT purposes will be £700,000

In summary: CGT liability is wiped out on death, and the beneficiary gets a “stepped-up” value for CGT purposes. The tax exposure shifts from CGT to IHT.

Real Life Case Study – CGT when gifting the property with mortgage

Nathan’s family owned three properties jointly between a brother and sister. They lived in one and rented the other two.

In 2024, the sister decided to move into one of the rental properties. The arrangement involved:

  • Remortgaging the main residence in the brother’s sole name, with the sister gifting her share
  • Remortgaging one buy-to-let in the sister’s name, with the brother gifting his share
  • No changes to the third property

Outcome:

  • The main residence was exempt from CGT due to principal residence relief (you do not have to pay capital gains tax on any profit if it has been your only or main home throughout the entire period of ownership.)
  • The buy-to-let property being gifted to the sister triggered CGT on the brother’s gain
  • Stamp Duty applied on both properties, calculated at 50% of the outstanding mortgage balance

Stamp Duty Land Tax (SDLT) on Gifts

While this topic deserves its own article, here’s a brief summary:

  • No SDLT is usually payable if the property is mortgage-free when gifted
  • If the property is mortgaged, the SDLT is based on the proportion of the outstanding mortgage transferred

Example: Gift with Mortgage

Let us suppose Alex owns a property worth £400,000 and gifts 50% to his daughter Melissa in 2025. If the mortgage at that time is £200,000, the consideration for SDLT purposes is £100,000 (50% of the mortgage). SDLT would then apply on this amount.

Final Thoughts

Gifting property is often part of long-term financial or inheritance planning, but the CGT implications can be significant—even when no money is exchanged.

Whether you’re:

  • Gifting to a child or spouse
  • Transferring to a trust
  • Inheriting or dealing with property between siblings

…understanding CGT and SDLT is essential.

At Nachu Finance, we help clients navigate these decisions with transparency and clarity. While we do not offer tax advice ourselves, we work closely with tax professionals and estate planning experts to guide you to the right solution.

Plan Smart, Gift Wisely

At Nachu Finance, we understand that gifting or inheriting property is rarely just a tax decision—it’s a family decision, a financial decision, and often, a legacy decision.

That’s why we offer holistic, well-rounded advice that considers:

  • How best to structure a property gift or inheritance from a tax and mortgage perspective
  • Whether to gift during your lifetime or leave assets through your Will
  • The impact on your broader financial plans, including protection, lending, and estate strategy

With the experience of guiding clients through these complex choices for almost two decades, a transparent, client-first approach, and access to trusted tax and legal professionals, we go beyond the transaction to help you do what’s best for your family—now and in the future.

Thinking about gifting property? Let’s explore the right way to do it.

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Planning Property Ownership with the Future in Mind

First-time buyer mortgage journey - step-by-step guide from Nachu Finance

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

The First-Time Buyer’s Mortgage Journey: A Complete, Practical Guide

First-time buyer mortgage journey - step-by-step guide from Nachu Finance

Who this is for

If you are buying your first home and want a clear, end-to-end view of what happens, in what order, and why — this guide is for you.

How to read this

This explains the ideal, logical sequence from first thought to mortgage offer and completion support.
In real life, you might join mid-way, skip a step, or loop back — that’s perfectly normal.
Use the anchor links and checklists to dip into the parts you need most.

Before You Start: What “Good Process” Looks Like

  • A clear picture of how much you can borrow, how much deposit you need, and what the total monthly cost could be.
  • An Agreement in Principle ready to show estate agents so your viewing and offer carry weight.
  • A researched product and term only once a property is agreed, not before.
  • A thorough application-prepping stage so there are fewer surprises later.
  • Prompt responses to lender queries and valuation logistics handled early.
  • A final mortgage offer that matches your illustration, checked for errors.
  • Ongoing rate watch right up to exchange if the lender reduces rates.

Scenario Assessment and Game Plan

Goal:
To answer four key questions with confidence:

  1. What is the maximum loan available to you?
  2. What deposit is needed and where will it come from?
  3. What one-off costs are likely at the start?
  4. What will your monthly payments look like under realistic options?

What we capture from you:

  • Employment and income details (including bonuses, overtime, or commissions).
  • If self-employed or a company director — profits, salary, dividends, latest accounts, or SA returns.
  • Credit commitments such as loans, cards, car finance, or student loans.
  • Family situation and foreseeable changes affecting affordability.
  • Deposit source and evidence.
  • Property preferences such as freehold or leasehold, service charges, ground rent, or new-build details.

Our unique approach
We prepare a personalised, dynamic spreadsheet that models:

  • Different property prices and deposits.
  • The impact of term or rate changes.
  • How your affordability and payments shift with each scenario.

This prevents wasted viewings and helps you and your family align on a realistic plan before falling in love with a property outside budget.

Outputs you receive:

  • A clear headline range for purchase price and loan.
  • Estimated upfront costs.
  • Indicative monthly payments under a few realistic setups.
  • A summary of the best-case pathway, subject to standard checks.

Agreement in Principle: Confidence for Viewings and Offers

What it is:
A lender’s non-binding confirmation that, based on declared information, your credit profile and circumstances appear acceptable for borrowing up to a stated limit and deposit.

What it is not:

  • Not a product choice or rate lock.
  • Not a full underwrite.
  • Does not require you to evidence income or deposit to the lender at that stage.
    (However, we still review these documents upfront to ensure everything aligns before applying.)

Possible outcomes:

  • Accepted for the requested loan and deposit.
  • Accepted but for a lower loan or higher deposit.
  • Referred for manual review.
  • Declined.

Why it matters:
Estate agents often ask for an AIP before viewings or when you make an offer. It demonstrates you’re financially prepared and serious about buying.

Tip:
We usually obtain the AIP at the most conservative deposit level you’re comfortable with. If you later choose to put in a larger deposit, that’s an easy adjustment.

Full Application: Only After Your Offer Is Accepted

When to choose products:
Only after the property and price are agreed. Before that, we show you ranges and examples — not specific products.
Once an offer is accepted, we refresh your spreadsheet and review:

  • Product style (fixed, tracker, discount).
  • Fixed period (two or five years, and whether flexibility is important).
  • Term, affordability, and how it affects long-term cost.
  • Fees and whether adding or paying upfront makes sense.
  • Leasehold and property-type considerations.

The key document you receive:
A detailed Mortgage Illustration that outlines your rate, fees, term, payments, and deposit.
This forms the foundation of the final mortgage offer, assuming there are no material changes.

Application-Prepping: The Extra Work That Saves Time Later

We resolve complexity before submission to minimise delays. Expect us to check lender criteria thoroughly and gather complete supporting evidence up-front, including:

  • ID and address verification.
  • Income documents: latest payslips, P60s for the last two years, and employment letter if required; or SA302s (Tax Calculations), Tax Year Overviews, company accounts, and accountant references for business owners.
  • Bank statements and explanations for unusual transactions.
  • Evidence of all credit commitments and deposit source.
  • Property details (lease, ground rent, new build warranty, etc.)

Why this matters:
It reduces back-and-forth, makes underwriting smoother, and surfaces deal-breakers early when there’s still time to adapt.

How long each step of the mortgage process typically takes

After Submission: Underwriting and Valuation

Lenders typically run these in parallel, though some prefer to finish underwriting before instructing a valuation, especially in specific or complex cases.

Underwriting — what to expect:

  • The case manager checks that all documents match the application.
  • Queries are common; some cases complete in a single round, while others require several iterations depending on complexity.
  • The lender focuses on identity, affordability, credit conduct, and how your deposit is sourced and evidenced.

Valuation — types, triggers and outcomes:

At this point, the lender instructs a valuation to confirm that the property is suitable security for the mortgage and that its value matches the agreed price.
You may not always see a valuer in person — sometimes it’s done digitally or from outside the property.

Mortgage valuation types and possible outcomes

The infographic above shows the three main valuation methods and the possible outcomes.
Here’s how to read it in context:

  • If the valuation comes back at the agreed price, the process moves smoothly to mortgage offer.
  • If it’s lower than the purchase price (a “down valuation”), we’ll discuss options — renegotiating the price, increasing your deposit, or exploring alternative lenders.
  • If the property is deemed unsuitable as security, this usually points to structural or legal issues. In such cases, we’ll reassess whether another lender or property is more appropriate.

If you’d like to understand the different types of property surveys and when each is recommended — for example, a RICS Level 2 (Homebuyer) or Level 3 (Building) report — read our detailed guide:
When to Get a Property Survey 

Mortgage Offer: Final Approval Before the Legal Stage

When the lender issues your mortgage offer, we:

  • Review it thoroughly to ensure it matches the illustration and key details.
  • Flag and correct any discrepancies with the lender.
  • Share the confirmed copy with you and your solicitor.
  • Update the estate agent that the offer is in place (without sharing private documents).

From this point, the legal work drives the timeline — searches, enquiries, and exchange.
We remain engaged until completion and monitor for potential rate reductions that may benefit you.

Rate Watch Between Offer and Exchange

If the lender reduces their rate and switching is practical before exchange, we assess whether it’s worthwhile and help you move to the better deal where feasible.

Your Role in Keeping Things Smooth

  • Provide complete documents promptly in the requested format.
  • Keep us updated on any job, income, or deposit changes.
  • Respond quickly to emails or document requests.
  • Facilitate access for surveyors and solicitor ID checks without delay.

What Happens After the Mortgage Offer

Your solicitor now takes the lead — handling searches, enquiries, exchange of contracts, and completion.
We remain available to coordinate lender conditions, monitor rates, and keep all parties aligned.

Next read: Understanding the Conveyancing Process When Buying a Property

Frequently Asked Questions

Yes — we’ll need your solicitor’s details before we submit your full mortgage application.
Having a solicitor in place helps avoid delays once the mortgage offer is issued and ensures your legal work can start promptly.
We’re happy to share a quote from one of the solicitors we work closely with for you to consider — entirely without pressure or obligation.

Yes, most lenders are comfortable with gifted deposits as long as there’s a formal letter confirming it’s a genuine gift, not a loan.
We’ll guide you and your family through what’s required so that the paperwork is exactly as lenders expect.

That’s absolutely fine — just let us know as soon as you can.
A change of job can affect how a lender assesses your application, but not always negatively.
We’ll review the new details, check lender criteria, and help you decide the best way forward without losing momentum.

Often yes, if there’s enough time before exchange and if the lender allows product switches.
We’ll assess whether it makes sense financially and, where worthwhile, help you move to the lower rate so you don’t miss out on potential savings.

It depends on the lender. Some carry out a soft search that doesn’t affect your credit score, while others perform a hard check that appears on your file.
We’ll always choose the most suitable route for your circumstances and discuss the implications before proceeding.

Your rate is locked only when we submit your full mortgage application with the chosen lender and product.
That’s why we don’t rush to select a deal too early — we’ll time it carefully so you can secure the best rate available once your property and price are confirmed.

It’s best to avoid taking on any new credit or making unnecessary credit applications until your property has completed.
Lenders may run additional checks before releasing funds, and new borrowing can affect your affordability assessment or credit score.
If something is essential and doesn’t increase your monthly commitments, that’s usually fine — but always check with us first to be sure.

How We Make Your Mortgage Journey Smoother

At Nachu Finance, we’ve supported hundreds of first-time buyers across a range of scenarios.
Here’s how we add value throughout your mortgage journey:

  • Whole-of-market advice: We assess options from across lenders to find what truly fits your circumstances.
  • Dynamic personalised spreadsheet: Unique to Nachu Finance — helping you visualise how deposit, term, or price changes affect costs.
  • Application-prepping approach: We identify and fix potential issues before submission, saving you time later.
  • Transparent communication: You’ll always know where your case stands, what’s possible, and what’s not.
  • Ongoing support: From rate watch to coordination with solicitors, we stay with you right up to key collection.

Explore more on our Mortgage Services page for detailed insights on first-time buyer, home mover, and specialist mortgage options.

Our Transparency Promise

When Things Don’t Go to Plan

While we’ll do everything possible to make your mortgage journey as straightforward as we can, the truth is that not every application runs exactly to plan.
At times, issues may arise that are outside anyone’s control — whether due to lender processes, valuation outcomes, or solicitor delays.

What we can promise, however, is that we’ll always be in your corner.

We’ll keep you informed, fight your case wherever possible, and work closely with all parties involved to achieve the best possible outcome for you.

Our role is not just to submit your mortgage — it’s to stand by you until your goals are achieved, with transparency, persistence, and care guiding every step.

Ready to Make Your First Home a Reality?

Buying your first home can feel complex — but with Nachu Finance by your side, it doesn’t have to be.
We’ll guide you from that very first calculation through to collecting your keys, ensuring each step is clear, compliant, and stress-free.

Our approach is more than just finding you a mortgage. We help you understand your numbers, prepare your documents, and structure your application so it fits perfectly with your circumstances. You’ll have full visibility at every stage, and confidence that your mortgage is right not only for today but for your long-term plans too.

Contact us today to begin your first-home journey with trusted, whole-of-market advice and genuine personal support.

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Essential Steps in Your Home-Buying Journey

Google search results versus professional mortgage advice - Nachu Finance

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

Why Professional Opinion Matters More Than a Google or AI Search

Google search results versus professional mortgage advice - Nachu Finance

General Search – The Starting Point

It is quite common for clients to begin their research by checking Google, using AI tools, or speaking to friends who have gone through a similar process. These are all good starting points to understand what is generally possible in the mortgage or property market and to familiarise yourself with key terms and concepts.

However, while Google searches, AI responses, and friendly discussions can help build general awareness, they cannot replace case-specific professional advice that takes into account your personal and financial circumstances.

If you are specifically interested in how advice-driven product selection differs from comparison websites, see our related article:

Why Personalised Mortgage Advice Goes Beyond Comparison Websites

The Limits of Generic Information

The information found through a Google search, an AI summary, or a general discussion with friends is, by nature, generic.It does not take into account:

  • Your income type or employment structure.
  • The property’s ownership model or intended use.
  • The lender’s current criteria.
  • Your residency or credit profile.

An AI answer can feel more tailored than a list of search results, because it responds to the specific question you asked. But it can only work with the information you have given it, and it does not know what you have not thought to mention. In practice, the details that change the outcome are often the ones a client would never think to include.

Mortgage lending, taxation, and property law all have layers of detail that differ from one case to another. What works well for one individual may not be suitable or even possible for another.

Generic search results versus case-specific mortgage advice comparison - Nachu Finance

Names in our case studies have been changed to protect client anonymity.

Ishan planned to use a gifted deposit for his purchase. A quick online search would have told him that lenders are happy to accept gifted deposits as long as the source of funds is evidenced and supported by a donor declaration.

While this is true in many standard residential purchases, Ishan’s purchase:

  • Was being made through a limited company,
  • Involved multiple shareholders, and
  • Related to a non-standard property: a multi-unit block under a single title.

Each of these narrowed the number of lenders available. Those who accept gifted deposits often do not accept multi-unit properties, and vice versa. For Ishan, the gap between what appeared acceptable online and what was actually possible was substantial.

Mr Nathan is a long-standing client and portfolio landlord. His buy-to-let properties form a significant part of his estate, and he wanted a long-term inheritance tax plan that would pass those properties on to his children fairly.

Before our next meeting, he shared details of his portfolio with an AI model and asked how the properties could be divided in an inheritance tax efficient way. After a number of iterations, the model produced a detailed plan. It worked through the property values, the outstanding balances and the remaining equity in each property, and showed how the split would stay equal between the children.

At the end of that plan came a short disclaimer. The model noted that it had not taken capital gains tax or stamp duty into account, and that the plan used direct transfers rather than any trust.

Those two lines carried a great deal of weight. When we worked through the figures for the Nathan family’s actual circumstances, the capital gains tax and stamp duty implications ran into hundreds of thousands of pounds. And because the transfers were direct, the properties would sit in the children’s own names with no protection once they arrived there – including if a child’s marriage were to break down later.

There was a second issue that no summary could have raised. Inheritance tax planning is not something to be started and settled in a single day. It is a long-term exercise, carried out in phases over decades and reviewed as circumstances change. The AI plan addressed the core objective of mitigating inheritance tax, and as a starting point for the conversation it had real value. It was not, and could not be, the plan itself.

Why Online Answers Can Be Skewed

There is one more limitation worth understanding, and it applies to search results and AI answers alike.

People rarely write about the times things went exactly as expected. They write when something went wrong. If someone has a high temperature, takes paracetamol and feels better in two days, they do not post about it. If the temperature persists because something else was going on, that is when it reaches a forum or an article — and that is what the search engine has to draw on.

The same is true in our field. Straightforward cases that complete without incident are rarely discussed online. The exceptions are. So the picture you get can be weighted towards the unusual rather than the typical — which is another reason to check what you find against your own circumstances.

Technology Should Enable Advice, Not Replace It

None of this is an argument against technology. We use it ourselves, a good number of our new enquiries reach us through Google and, increasingly, through AI-assisted searches, and clients who arrive having done their own reading usually have sharper questions and clearer priorities.

Our position is a simple one: let technology enable the advice and research process, not replace it. In an area as personal and as long-term as financial planning, the analysis needs to sit alongside someone who knows your full circumstances and carries responsibility for the recommendation.

Why Professional Advice Holds Greater Weight

Professional opinion is built on understanding not just what the rules say, but how they are applied in practice.
It involves:

  • Interpreting lender and solicitor criteria within the context of your case.
  • Balancing compliance, affordability, and timing.
  • Ensuring that what appears possible in theory is achievable in reality.

A professional adviser also carries regulatory accountability — meaning the guidance you receive must be suitable, compliant, and in your best interests. That level of responsibility does not exist in a Google search, an AI response, or a conversation with friends.

Research Is Useful – Validation Is Essential

Doing your own research is helpful and can make conversations more meaningful. Bringing an AI summary to a meeting is welcome, not unwelcome; it often tells us exactly what matters to you.

But before proceeding with decisions or forming expectations, it is vital to validate that research with a qualified professional. A generic Google answer or AI response can inform you of what is common, but professional advice ensures that what you are planning is achievable and acceptable for your specific situation.

The key takeaway: general searches are a good place to start — professional advice ensures you finish right.

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Make Better-Informed Mortgage Decisions

Wooden letter tiles spelling "rent out" versus "sell" on a split blue and yellow background, illustrating the choice homeowners face when moving

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

Moving Home: Should You Let Out Your Current Property or Sell It?

Wooden letter tiles spelling "rent out" versus "sell" on a split blue and yellow background, illustrating the choice homeowners face when moving

Unlike a first-time buyer, a homeowner looking to move has an extra decision to make before anything else: what happens to the property you already own?

Broadly, there are two routes.

  1. Retain and let out your current property, and buy the new one as an additional property.
  2. Sell your current property and buy the new one at the same time — which usually means being part of a chain.

Each route has different financial, practical and lifestyle implications. This article sets out both so you can work out which suits your circumstances, and we close with a side-by-side comparison and some common questions.

Option 1: Keep your current property and let it out

Before looking at the numbers, there are two questions to answer honestly. You need a “yes” to both.

Question 1: Do your finances allow it?

When you sell, all of the equity in your current home is released to put towards the next one. When you keep it as a rental, that is not the case.

  • Equity you must leave in the property. As an absolute minimum, lenders expect you to leave 25% equity in the property you are letting out. Depending on the rental income the property can achieve and how the lender stress-tests it, the amount you must leave in may be higher.
  • Additional stamp duty. Buying a new home while keeping your existing one means the purchase is treated as an additional property. The additional-rate surcharge currently stands at 5% on top of the standard rates. See our guide to stamp duty for home movers for how this is calculated.

So the question is whether, after leaving at least 25% equity behind and paying the higher stamp duty, you still have enough to fund the deposit and costs on the new property.

Question 2: Do you have the appetite to be a landlord?

Letting out a property is not simply another investment. It comes with ongoing legal, regulatory and practical responsibilities — and the regulatory bar has been rising steadily over recent years. Two of the most common practical points to plan for: you’ll need landlord insurance (standard buildings insurance doesn’t cover a let property), and the property will need to meet the minimum EPC rating required for rental properties, with the bar expected to rise further. Before committing, read our guide to the responsibilities of being a landlord and be honest about whether you have the time and the mindset for it.

If the answer to both is yes

You are in a strong position. Because you are not relying on a sale to fund your purchase, your new purchase does not fall within a chain, which removes one of the biggest sources of stress and delay in moving home.

The mortgage arrangement you will be using on your current property is technically called a let to buy mortgage — you are letting out your current residential property with a view to buying a new one. This is a well-established arrangement and we cover it in detail in our Let to Buy mortgage guide. Two points worth knowing at this stage:

  • Simultaneous completion. Lenders expect the let to buy remortgage on your current property and the purchase of your new home to complete on the same day, so that you move out of the current property and it becomes available to let.
  • What determines how much you can raise. The current market value of the property and the rental income it can achieve are the two key factors in how much capital a let to buy mortgage can release towards your new home.
  • Consent to let. If you have an existing residential mortgage on the property, you’ll need your lender’s consent to let it out — either as a standalone consent or as part of the let to buy remortgage. Don’t assume this is automatic; check before you commit.

Option 2: Sell your current property and buy the new one

The financial side

Financially, this is the simpler route.

  • All of your equity is released and available for the new purchase.
  • No additional stamp duty is payable, provided you meet HMRC’s conditions and can show you are replacing your main residence.
  • No landlord responsibilities — if being a landlord does not appeal, this route avoids it entirely.

The practical side

The trade-off is that you will be in a chain, and your sale and purchase must progress in step.

  • Completion has to be aligned. You hand over the keys to your buyer on the same day you collect the keys to your new home, and move house that day. Completion day itself can be logistically demanding.
  • Everyone in the chain must be ready. If your buyer has their own sale to complete (a downward chain), or your seller has their own purchase (an upward chain), every party has to reach the same stage before anyone can complete.
  • One end often moves faster than the other. In practice, we regularly see clients who have found the property they want to move to but have no buyer for their own home — or who have a buyer lined up but nowhere to move to.

None of these challenges is insurmountable, and buying and selling at the same time is done successfully every day. But they should be planned for, and there is no option for managing a chain that comes without some disadvantage of its own. See our guide to breaking the chain for the main approaches.

A third route: buy first, sell later

There is a middle path for those whose finances are not dependent on the sale.

If you can fund the new purchase without the proceeds of your current home, can afford the additional 5% stamp duty up front, and would prefer not to be in a chain — but also do not want to keep the current property long term — you can:

  1. Buy your new home first, paying the additional-rate stamp duty.
  2. Sell your current property afterwards.
  3. Reclaim the additional stamp duty from HMRC once the sale completes (subject to the time limit — see the FAQ below).

This suits a specific set of circumstances: finances that are not restricted, and a clear intention to sell rather than let out.

Letting out vs selling: side by side

Infographic comparing letting out versus selling a current property when moving home, across equity released, stamp duty, chain, timing, borrowing, responsibilities, tax and longer-term position

Frequently asked questions

Technically, yes. If you decide to retain the property but would prefer to hold it through a limited company rather than personally, that is an option you can explore. Whether the numbers make sense depends on your circumstances — in particular, moving a property from personal names into a company is treated as a purchase by the company, so stamp duty is payable on the transfer. Our article on transferring a property from personal names to a limited company covers the considerations in detail.

Yes, this is possible, but two timing rules matter.

  • Stamp duty reclaim. If you have paid the additional 5% stamp duty on your new home and want to reclaim it, HMRC requires the sale of your previous main residence to complete within three years of buying the new one.
  • Renters’ Rights Act. Once you have let the property, you cannot serve notice to a tenant on the grounds that you intend to sell within the first 12 months of the tenancy. Plan your timing accordingly — a short let is a minimum one-year commitment in practice. Our Renters’ Rights Act guide explains the position in full.

Being a landlord is entirely achievable, but it is a regulated activity and the government has made it more so over the last few years. If you are prepared to understand the requirements, keep on top of them and manage the property properly, letting out your current home is a perfectly realistic option. Before you commit, make sure you have read the responsibilities of being a landlord, and be confident you have both the time and the attitude to give it — it is an additional ongoing commitment, not a one-off decision.

The two routes are taxed differently. If you let out your current property, the rental income is taxable, and you may face Capital Gains Tax when you eventually sell it. If you sell now instead, main residence relief will usually mean no Capital Gains Tax is due, since you are selling the home you have been living in. Tax treatment depends on individual circumstances, so it’s worth factoring into your decision alongside the financial and practical points above.

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Plan Your Move With Confidence

Family walking home to their house — life insurance through work versus your own cover

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

I Have Life Insurance Through Work — Is That Enough?

Family walking home to their house — life insurance through work versus your own cover

The short answer: Employer life cover — usually called death in service — is a valuable benefit and you should make the most of it. But it is calculated on your salary rather than your family’s needs, it ends the day you leave, and it almost never gets reviewed. The balanced approach is to count it, reduce your own cover accordingly, and never rely on it alone.

“I already have cover through work” is one of the most common things we hear when life insurance comes up during a mortgage. It is a fair point — and often a good benefit. This article explains what death in service does well, where it falls short, and how we combine it with cover of your own so the foundation of your family’s financial plan doesn’t depend on where you happen to work.

First, credit where it’s due

We have never advised a client to ignore or under-use the life cover their employer provides. Death in service has real advantages:

  • Lighter underwriting. Depending on the employer and the provider, group schemes usually involve far less individual health underwriting than a personal policy, which is assessed thoroughly on your own medical history. For anyone whose health would make personal cover expensive or unavailable, work cover can be the most valuable protection they hold. It is worth checking what your own scheme actually does — cover above a certain level is sometimes underwritten individually.
  • Economies of scale. Whether the employer pays or you contribute, group cover is generally cheaper per pound of cover than a personal policy — and smokers in particular benefit, as personal premiums can be significantly higher.
  • It lowers what you need to buy yourself. Every pound of work cover is a pound of personal cover you don’t have to pay for during your working years.

If your employer lets you increase your multiple for a modest contribution, it is usually worth doing. Our point is not “don’t rely on work cover”. It is “don’t rely on it alone”.


Do you know what you actually have?

Here is something we see constantly: clients can tell us to the pound how much personal life cover they took out, but very few can say how many times salary their work scheme pays. That tells you how little attention this benefit gets once the job starts.

Typical death in service pays three to five times salary. Three or four times is the norm; four and five times usually appear where the employee has opted in at extra cost or the employer uses it as a recruitment incentive. It is worth checking your contract or benefits portal today — and worth checking whether the additional items on your payslip are covered, or only your basic pay.

Where employer cover falls short

  1. It is based on your basic salary, not your family’s needs. A multiple of basic pay ignores your mortgage balance, other commitments, how many dependants you have and how old they are. It usually also ignores bonuses, overtime, stock options and any second income — so for many people the real gap between “what work pays out” and “what the family would need” is wider than the headline multiple suggests.

  2. It ends when your employment does. Change jobs, take a career break, reduce your hours, become a contractor or go self-employed and the cover stops. Exactly when it stops varies, so check your scheme’s cessation period or date. If your health has changed in the meantime, replacing it can be expensive or impossible.

  3. You don’t control it. The employer chooses the provider, the multiple and the scheme trust. You can usually nominate beneficiaries, but you cannot choose your own trustees, structure the trust around your estate planning, or adjust it as your family changes. Your employer can also change or reduce the scheme.

  4. It is set on day one and hardly ever reviewed. A personal policy gets reviewed when you buy a property, have a child or remortgage — because we are in touch at those moments. Work cover was decided when you signed your contract and, in our experience, is almost never revisited at the financial junctures that matter.

  5. It doesn’t lock anything in. A personal policy fixes your terms and premium at the point you apply, while you are young and healthy, for the whole term. Work cover gives you nothing to keep if you leave.

Employer cover vs your own cover — at a glance

 Employer death in serviceYour own life cover
How muchFixed multiple of salary, usually basic pay only (typically 3–5×)Sized to your mortgage, commitments and dependants
Who owns itThe employer’s schemeYou
If you leave your jobEnds — timing varies by scheme, check the cessation dateContinues unchanged
UnderwritingGroup basis — usually lighter, and provider-dependent; larger amounts may be underwritten individuallyFully underwritten on your health — cheaper when young and healthy, and terms locked in
Trust and beneficiariesNomination only; scheme trustees decideYou choose the trust, trustees and beneficiaries
Reviewed when life changesRarelyAt every mortgage, remortgage and family milestone
Cost to youFree or low costMonthly premium — reduced by whatever work already provides
Best forA valuable base layer, especially if health limits personal coverThe part of the foundation that stays with you


The balanced approach

Life insurance sits at the base of the financial planning pyramid — everything else you build (savings, investments, pensions) assumes your family can keep the house and their standard of living if you are not there. It is too important to leave dependent on your employer’s payroll.

So our approach is simple:

  • Count what work gives you. We record the multiple and the salary definition, and we treat it as real cover.
  • Reduce your own cover accordingly. There is no sense paying for overlapping cover. Work cover brings your personal premium down.
  • Never let it be the only layer. Your own policy, sized to the mortgage and the family, is the part that moves with you.
Infographic: a house and family resting on work cover alone versus work cover plus a personal life insurance policy

A top-up matters most if you have a residential mortgage, dependent children, or a household that relies heavily on your income. If you are self-employed or a contractor, there is no work layer at all — every part of your protection has to be arranged by you.

How much top-up? There is no formula. We size it to your individual circumstances — mortgage balance, other commitments, dependants and their ages, what work already provides and what you are comfortable paying. That is where personalised advice earns its place over a one-size-fits-all multiple.

Life changes. Work cover doesn’t come with you.

The scenario we see most often is the move from permanent employment to contracting or self-employment — particularly in IT, construction and among medical practitioners, where day-rate or locum work can be significantly more rewarding. The conversation is usually about income and tax. The death in service benefit gets noticed late, if at all.

By the time it does, the client is typically in their forties, may have a medical history that didn’t exist when they started their career, and is now paying full price for cover that could have cost a third as much had it been started at 25 and simply kept. For company directors there is a tax-efficient route — a Relevant Life Plan — but it still has to be arranged, and it is still underwritten on your health at that point.

death-in-service-when-life-changes.png Infographic: what happens to death in service cover versus your own policy when you change jobs, go self-employed, take a career break or your health changes

We saw exactly this with a client who moved to day-rate contracting within a year of buying his home. His death in service ended with the job, and we rebuilt his protection through his own limited company — one of several cases we set out in our
Life Insurance Review  article


The estate planning angle

Because we also handle estate planning and have supported families through probate, we see what happens after a claim — not just at the point of sale. Death in service is usually paid through the employer’s discretionary trust and normally sits outside the estate for inheritance tax, so that is not the issue. Four other things stand out:

  • Adequacy is only tested at the claim. This is the one that catches families out. A sum assured that felt sensible when the mortgage was arranged often turns out not to be enough to replace a breadwinner and let the family carry on as before. The real requirement is far more than the mortgage balance — let alone what an employer provides as a multiple of salary. By the time this becomes clear, nothing can be done about it.
  • Liquidity for inheritance tax. Where IHT is due, it has to be paid before the grant of probate is issued, and within six months of the end of the month of death — yet the estate itself is locked until that grant comes through. A personal policy in trust can provide the cash so the family is not forced to sell, borrow or use their own savings.
  • With your own policy you choose the trust, the trustees and the beneficiaries, and you can update them as children become adults or circumstances change. A work scheme gives you a nomination form, and the trustees decide.
  • A personal policy written in trust pays out on proof of death, without waiting for probate. That money is often needed within weeks, not months.

Readmore:  placing your life insurance under a trust  and  life insurance for inheritance tax planning

Real-life case studies

Names and some details have been changed to protect client confidentiality

Dinesh  was the sole breadwinner for his family, with a son in the middle of his A-levels. When he bought the family home he had four times salary through work and initially felt that was enough. Given the mortgage balance, a dependent child and one income, we recommended an additional level cover of £500,000, written in trust.

He died unexpectedly a few years later. At that point the property was worth around £650,000 with a mortgage of about £425,000. His death in service paid four times his £80,000 basic salary — £320,000 — and the personal policy paid £500,000, immediately and outside the estate. Together, £820,000 cleared the mortgage and left a surplus for the family to replace his lost income.

Two years on, at our next review, his son had started his undergraduate course at a leading UK university. The family had carried on without financial disruption. Had the family relied on the work cover alone, it would not have cleared the mortgage, let alone supported them afterwards. And because the work cover existed, Dinesh had paid for a smaller personal policy than he otherwise would have — the balanced approach, working as intended.

Karthik, 43, had worked in IT for several years on a £72,000 salary with a generous 4.5× death in service — £324,000 of cover. During one of our regular reviews he mentioned an offer to move to a contract at £525 a day, five days a week: comfortably over £120,000 a year. Financially, an obvious move.

What hadn’t featured in his thinking was that the £324,000 would end with his employment. Replacing it with his own policy was quoted at around £96 a month on standard terms. But Karthik had a medical condition that had developed in the previous five or six years, and the best terms available carried a 50% loading — roughly £144 a month. Had he started a policy of his own at 25 and simply kept it, the premium would have been in the region of £30 a month, on standard terms, locked in for life.

He went ahead. The increase in income more than justified the cost. But it was a cost that only existed because the foundation had been left to the employer.

Richard originally held a Relevant Life Plan through his limited company. When he closed the business and moved into employment, his new employer provided death in service equal to four times salary. He wanted the same overall protection as before, with the new work benefit taken into account.

We carried out a full review, cancelled the Relevant Life Plan, and arranged personal cover sized to top up the work benefit to the level he was comfortable with — keeping his premium as low as the work cover allowed. Protection is not static: it should change as your employment does, and it needs an adviser who looks at every source of cover together.

Our Transparency Promise

Full Disclosure, Complete Peace of Mind

The right disclosure, from the start. A life policy is only worth having if it pays out. That depends on the application being accurate. Before we submit anything, we discuss your medical and lifestyle circumstances in detail and carry out a pre-application check so you know the terms you are likely to be offered — no surprises. With most insurers we can share a copy of the completed application with you to confirm every answer before it goes in. It is a little more work now, and it is how we keep the risk of non-disclosure at claim stage as low as it can be.

Let’s look at your cover from every angle

Life insurance is the foundation of any family’s financial plan, and it deserves more care than a benefits form filled in on your first day. At Nachu Finance we help families get on the property ladder and we help them through probate and estate planning — so we see life cover from both ends: what it costs to set up, and what it does when it is needed. And because we stay in touch through every mortgage, remortgage and family milestone, your cover does not sit untouched for twenty years — we keep reviewing it as your mortgage, your income and your family change.

Start your life insurance, or have your existing cover — including what you get through work — reviewed properly, and reviewed again as life moves on. Your first meeting with us is free of charge.

Frequently Asked Questions

For some households, yes. For most with a mortgage and dependants, it isn’t. The test is not the multiple; it is whether the payout would clear the mortgage and replace enough income for the family to carry on. We run that calculation with you and count the work cover in full before recommending anything.

No. Keep it, and increase it if your employer lets you do so cheaply. Your personal policy is sized around it.

It normally ends when your employment ends, though the exact cessation date varies by scheme. Some schemes offer a continuation option, but this is not guaranteed and it is not in your control — it depends on the terms of the employer’s scheme. If you are planning a move to contracting or self-employment, arrange your own cover before you resign, while you are still covered.

Yes. You can hold cover from several sources. When you apply for a personal policy you declare the cover you already have so the insurer can assess the total sensibly.

This is exactly where work cover earns its place — maximise it. We will then research the market for insurers likely to take a favourable view of your circumstances, and be honest with you about the likely terms before you apply. Some cover of your own, even at a modest level, is usually still worth having.

Most schemes are already written under the employer’s discretionary trust, and you complete a nomination form. That usually keeps the payout outside your estate, but you don’t choose the trustees or the terms, and nominations are easily forgotten. A personal policy lets you set the trust up the way your estate plan needs.

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Keep building the foundation

Let to buy mortgage explained: keep your current home as a rental and buy a new home

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

Let to Buy Mortgage Explained: How It Works & Key Considerations

Let to buy mortgage explained: keep your current home as a rental and buy a new home

A Let to Buy mortgage is when you remortgage your current residential property onto a buy to let mortgage so that you can move into a new residential home without selling your existing one. This structure enables homeowners to keep their current property as an investment, rent it out, and at the same time proceed with the purchase of a new residential property.

What makes Let to Buy slightly different from a standard buy to let remortgage is the connected home move. You are turning your present home into a rental property specifically because you are purchasing and moving into a new residence. This is why lenders treat Let to Buy as a distinct category with its own conditions.

Why a Let to Buy Mortgage Exists

A Let to Buy mortgage is often used when:

  • You wish to keep your existing home as an investment property
  • You need to release equity from the current home to help fund the deposit for your onward purchase
  • You prefer not to sell the property but require a mortgage that allows you to legally let the property out

Once the Let to Buy mortgage completes, the lender expects that you no longer live in that property.

Simultaneous Transactions

A key concept in Let to Buy applications

Most Let to Buy transactions require simultaneous completion between:

  • The Let to Buy remortgage of the existing home
  • The purchase of the new residential property

Lenders expect both to complete together because:

  1. Once they issue a Let to Buy mortgage, you are no longer permitted to occupy the former home.
  2. If you are raising funds from the existing property to help with the new purchase, the purchase cannot complete unless the Let to Buy remortgage completes.
  3. The two transactions are financially and legally dependent on each other, similar to how a sale and purchase work together on the same day.

This simultaneous structure ensures that the equity release, legal change of status, and occupation rules all align within the same completion window.

How simultaneous completion works on a let to buy remortgage and onward purchase

When You Do Not Need a Simultaneous Transaction

A simultaneous completion is not required if you do not need to release funds from your current home for the new purchase. In that case:

  • You may complete the new residential purchase first
  • Move into the new property
  • Prepare the former property to be rented out
  • Then apply for either:
    • A Let to Buy remortgage at a later date, or
    • Obtain consent to let temporarily and switch to a buy to let mortgage later

When you are planning to buy first and rent out the current residential property at a later time you may need to get evidence of the expected rental income from an ARLA recognised letting agent for the purpose of the new mortgage on the property you are going to purchase. This letter would be needed to evidence that rent can offset the mortgage commitment on the current residential mortgage.

What you cannot do is complete the Let to Buy remortgage first, remain living in the property, and delay the residential purchase. The occupation rules do not allow this.

Transferring the Former Residential Property into a Limited Company

An alternative to retaining the former residential property under a Let to Buy structure is to transfer the property into a limited company and then proceed with the new residential purchase separately.

This approach can be suitable in certain circumstances, particularly for clients considering long-term property investment through a company. However, it is not appropriate for everyone and requires careful consideration.

While Capital Gains Tax does not usually apply (subject to conditions being met and only for the period you have occupied the property) when transferring a former main residence due to principal private residence relief, Stamp Duty Land Tax (SDLT) is a key factor. The limited company is treated as a separate buyer, meaning SDLT is calculated on the full market value of the property and will include the additional property stamp duty (higher rate surcharge).

There are also additional costs and practical implications, including:

  • Two legal transactions (sale from personal names and purchase by the company)
  • Two sets of solicitor fees
  • Valuation and mortgage arrangement costs
  • Ongoing company running and compliance expenses

For some clients, particularly those buying a significantly more expensive residential property than the value of their current property, this structure can work well. For others, it may add complexity and cost without delivering sufficient benefit. The decision should always be assessed in the context of personal circumstances, long-term plans, and overall affordability.

You can read more in our detailed article on transferring property from personal name to a limited company,  including the Real life Case Study: A Former Home Becomes a Tax-Efficient Investment, which explores this option in greater depth.

Prakash and Meena

Prakash and Meena lived in a two-bedroom flat that no longer met their growing family’s needs. They found a three-bedroom house they wished to purchase, but they did not want to sell their existing flat as they viewed it as a strong long-term investment.

They required an additional £50,000 from the flat to complete the new purchase.
We arranged:

  • A Let to Buy remortgage with BM Solutions on an interest-only basis, supported by the expected rental income
  • A new residential mortgage with Halifax

Both transactions completed on 12 June.
The solicitor received the Halifax mortgage funds first. On the completion day (12th June), the solicitor:

  • Drew down the BM Solutions Let to Buy mortgage
  • Repaid the existing Santander residential mortgage
  • Used the remaining £50,000 toward the deposit for the new purchase

Because the clients needed the equity release, the simultaneous completion structure worked perfectly.
Had they not required equity from the flat, they could have purchased the new home first and dealt with the remortgage later.

Frequently Asked Questions

The mortgage conditions stipulate that once the Let to Buy mortgage completes and you own your new residential home, you must no longer occupy the former property.
In practice, lenders understand there may be a short transition period to clean, prepare, or repair the property before letting it. The lenders generally allow a reasonable period to prepare the property for letting, but the clear expectation is that the property becomes let-ready as soon as reasonably possible.
It is also in your interest financially to avoid paying two full residential-style mortgages longer than necessary.

Lenders know the property is not yet let.
You can research the likely market rental income using letting agents or online portals.
The lender’s surveyor (valuer) will confirm:

  • The property value
  • The expected rental income

Your mortgage offer will be based on the valuer’s confirmed rental assessment.

Once the Let to Buy mortgage starts, there is effectively no practical difference. The property is treated as a buy to let property.

The differences arise before completion:

  • The property is not yet let
  • There is a connected residential purchase
  • Some lenders have a dedicated product range or slightly different criteria for Let to Buy
  • Some lenders who offer buy to let mortgages may not offer let to buy mortgages and others may have additional conditions that apply for a let to buy mortgage

After completion, it functions the same as any buy to let mortgage.

Yes.
Although buy to let mortgages are generally unregulated, a Let to Buy remortgage is treated as consumer buy to let because the loan relates to a property that was your main residence.
You can still choose interest only or repayment options, but the advice and application fall under regulated mortgage rules.

Yes.
Although residential mortgages are typically repayment-based, lenders are comfortable offering interest only on Let to Buy mortgages, provided it suits your circumstances and the rental income supports the structure.

Legally no, but practically it is strongly recommended.
Using one solicitor avoids:

  • Delays in transferring funds
  • Coordination gaps between the two transactions
  • Increased administrative costs

A single solicitor ensures the simultaneous completion can progress smoothly.

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Life insurance review meeting with adviser checking policy documents to keep family cover up to date

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

Life Insurance Review: Why You Should Revisit Your Existing Policies

Life insurance review meeting with adviser checking policy documents to keep family cover up to date

Life insurance, critical illness cover, and income protection are essential pillars of family protection. Yet, once policies are in place, many people rarely revisit them.
At Nachu Finance, we believe a periodic review of your existing life insurance can make all the difference — ensuring your cover remains relevant, accessible, and effective when your family needs it most.

Make Sure the Policy Is Accessible

Before anything else, ensure that your family knows what policies you hold, who the providers are, and where to find the documents.

It is surprisingly common for families to be unaware of the details of existing policies. If you find it difficult to locate your documents while everything is going well, imagine how challenging this could be during a crisis.
Keep your policies accessible — ideally in both digital and physical form — and make sure immediate family members or adult children know where to find them.

Place Your Policy Under a Trust

Placing a life insurance policy under a trust ensures that proceeds are paid quickly and tax-efficiently to your chosen beneficiaries.
If your policy isn’t already under a trust, we strongly recommend setting this up.

If it is already under a trust, ensure the trustees’ details are up to date — especially if children have now become adults or if any trustee is no longer suitable to act.

Read more in our related article: Why Your Life Insurance Policy Should Be Placed Under a Trust

Older Policies: Hidden Gems Worth Keeping

Older life insurance plans can often be genuine hidden gems.
Premiums are based on your age and health at the time you apply, which means policies taken out years ago often benefit from significantly lower, locked-in premiums and medical terms that may no longer be available today.

Before cancelling, altering, or replacing an existing policy, it is essential to seek professional advice. At Nachu Finance, we review older policies with care to ensure they remain relevant to your current needs, and we rarely recommend cancelling them unless there is a clear and meaningful benefit.

Because premiums rise sharply with age, older plans can offer outstanding long-term value compared to arranging cover later in life. Our premium comparison chart by age clearly shows how starting early keeps costs lower for the entire duration of the policy — you can view it here Don’t Just Buy a Home-Protect It Too  for a clearer picture.

Extending or Increasing an Existing Policy

It is natural to wonder whether an existing policy can simply be extended to cover a longer term or increased to a higher amount.
In most cases, insurers will not allow an increase in cover or extension of the term without full medical reassessment, as this changes the original risk profile.

Our approach is to:

  • Keep your existing policy as it is.
  • Add a “top-up” policy for additional cover or a longer term if needed.

This way, you retain the advantages of your older policy while ensuring your family remains fully protected.

Ensuring Your Cover Is Still Relevant

Life events that call for a life insurance review including marriage, a new home, children and a change of employment

Life evolves — so should your insurance.
Events such as marriage, buying a new home, having children, or changes in employment (for instance, moving from employed to self-employed) all affect your protection needs.

A periodic review helps you check whether:

  • The level of cover matches your mortgage balance and family needs.
  • Your term still aligns with your working years.
  • Any employer benefits or other cover overlap with your personal policies.
Alt text Dos and don'ts when reviewing an existing life insurance policy

Real-life Case Studies

Here are three real-life examples that show how a life insurance review can make a meaningful difference at different stages of life. Each case has a different outcome, but in every situation the review still proved to be the right and sensible step.

Ishan & Sitara

Ishan bought his first property in 2017 for £320,000 with a £250,000 mortgage. At the time, he took out £250,000 of life cover and £100,000 of critical illness cover in his sole name.

When he returned in 2023, he was now married to Sitara and the couple were buying a new family home for £610,000. During our review, we found that Ishan’s historic policies offered excellent terms and very competitive premiums, which would be hard to replicate today.

We therefore kept both existing policies in place, placed his life cover under a trust, and recommended top-up life cover to match his new financial responsibilities. Since Sitara had no protection at all, we also arranged suitable life and critical illness cover for her.

This is a textbook example of why older plans should not be cancelled automatically. With a review, the couple were able to:

  • retain valuable historic cover
  • place the policy under trust
  • top up protection to match their new life stage
  • ensure both partners were fully covered

Felix & Amy

Felix and Amy came to us in 2021 for a remortgage. They had originally purchased their home in 2015 and arranged their life insurance directly with the insurer at the time.

When we asked for their policy documents, they initially struggled to locate them — a common issue that becomes critical during a claim. After some effort, they shared a copy with us and also made sure their family knew where the documents were safely stored.

Following a full review, we concluded that their existing life and critical illness policies were still appropriate for their current circumstances. No top-up cover was needed, but we placed their existing plans under trust and securely stored copies of their documents in their client folder.

Although no new insurance was taken, the review still delivered meaningful benefits:

  • policy documents were located and securely stored
  • the family now knows exactly where to find them
  • the plans were placed under trust for efficient payout
  • reassurance that their existing cover remains fit for purpose

This case shows how valuable a review can be even when no policy changes are required.

Vivan & Rebecca

Vivan and Rebecca approached us around 11 months after their original life insurance was set up at the time of their property purchase. Both were employed when the policies were first taken out.

Within a year, Vivan had moved from employment into a day-rate contracting role through his own limited company. This meant he no longer received the death-in-service benefit he previously enjoyed from his employer.

During the review, we kept Rebecca’s policies unchanged, as her circumstances remained the same. For Vivan, we recommended restructuring his protection by:

  • cancelling his new-but-still-young personal life cover
  • replacing it with a Relevant Life Plan to benefit from significant tax efficiencies
  • increasing the level of life cover to reflect his new responsibilities and lack of workplace benefits

We also reviewed critical illness cover. Although a higher amount would have been sensible, Vivan decided not to increase it for now due to cost considerations.

This case highlights how a review can help align protection with changing employment circumstances — especially when moving to self-employment or contracting.

The Nachu Finance Way

Nachu Finance review and top-up approach keeping the existing life insurance policy and adding top-up cover where needed

At Nachu Finance, we appreciate that older policies can hold immense value.
When we review your existing cover, we:

  • Check if it remains suitable for your current family and financial circumstances.
  • Help optimise it — including setting up or updating the trust.
  • Securely store copies of your policies in your client file, so your family can easily access them in the event of a claim.
  • Review both policies arranged by us and those you arranged elsewhere.

Even if no changes are needed, the reassurance that your policy is still fit for purpose is a valuable outcome in itself.

Frequently Asked Questions

No. The insurer bases its terms on your health and lifestyle at the time of application.
Once the policy is live, there is no obligation to update them about later changes.

Yes. You can replace or add trustees at any time.
We always recommend reviewing the trustees during your periodic insurance review to ensure they are still appropriate and willing to act.

Yes. You can hold multiple policies with different providers.
At application, you must declare any existing cover so the insurer can assess your total cover amount correctly.

Absolutely.
For clients whose policies were arranged through us, claim support is fee-free.
We believe compassionate, expert help at such a crucial time is an essential part of our service.

Yes. Many people keep their older policies because they offer lower premiums and favourable terms, and simply add a top-up policy when their protection needs increase. This is completely normal, and it allows you to retain the benefits of your historic cover while ensuring your overall protection keeps pace with life changes.

Our Transparency Promise

Full Disclosure, Complete Peace of Mind

At Nachu Finance, we insist that all applications are made with full and honest disclosure of health, lifestyle, and smoking status.
We review every detail with you before submission, so the insurer receives accurate information.

We would rather an insurer take extra time to verify your details now than risk a claim being declined later for non-disclosure.
This careful approach protects your family’s peace of mind and ensures that your policy pays out when it matters most.

Let Us Review Your Policy

As holistic advisers, we see life insurance as a core part of family financial planning.
Our transparent, no-pressure approach means we’ll only recommend action when it’s genuinely in your favour.

Reach out to Nachu Finance for a free, transparent review of your existing life insurance.
We’ll give you an honest assessment and, if needed, help you:

  • Place the policy under a trust
  • Adjust or top-up your cover
  • Optimise your family’s protection for today and the years ahead
Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Continue the Best Practices of Family Protection

EPC rating A to G for property mortgage approval UK - energy efficiency impact on mortgage eligibility

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

EPC Ratings and Mortgages: What Buyers and Landlords Need to Know

EPC rating A to G for property mortgage approval UK - energy efficiency impact on mortgage eligibility

When buying or letting out a property  the EPC rating can have a larger impact than expected as it is not just legal compliance. It can influence your mortgage options, ongoing energy costs, and even your long-term returns. Whether you are a first-time buyer, a home mover, or a landlord, understanding how EPC ratings fit into the bigger picture is essential.

When applying for a mortgage, particularly for buy-to-let or investment properties, the Energy Performance Certificate (EPC) is NOT just a formality. It carries financial, regulatory, and environmental importance.

At Nachu Finance, we are not energy advisers, but we do take a holistic approach to mortgage planning, and EPC considerations are an important part of the advice we provide.

What Is an EPC and Why It Matters

An Energy Performance Certificate (EPC) provides an energy efficiency rating for a property on a scale from A (most efficient) to G (least efficient). It is a legal requirement in the UK when:

  • Selling a property
  • Letting out a property

The EPC is valid for 10 years and can be easily checked and downloaded via the government portal: https://www.gov.uk/find-energy-certificate. All you will need is the postcode and door number. There is no cost involved in downloading the EPC certificate.

Minimum EPC Requirements for Buy-to-Let Mortgages

To let out a property, it must have a minimum EPC rating of E. Properties rated F or G cannot legally be rented, and mortgage lenders will typically reject applications for such properties until the EPC is improved.

So, if you’re looking to mortgage a property without a valid or acceptable EPC, this must be addressed before proceeding with the mortgage application.

Confirmed: EPC C Required for All Rentals by October 2030

In January 2026, alongside the Warm Homes Plan, the UK Government confirmed its final policy position on minimum energy standards for the private rented sector. All rental properties in England and Wales must achieve a minimum EPC rating of C from 1 October 2030.

Key points for landlords:

  • Single deadline – the earlier proposal of 2028 for new tenancies has been dropped. One deadline of 1 October 2030 now applies to all tenancies, new and existing. 
  • Cost cap – landlords will be required to spend up to £10,000 per property (or 10% of the property value, if lower) towards reaching EPC C, with exemptions available where the standard still cannot be met. 
  • Early compliance protected – properties achieving an EPC C before 1 October 2029 under the current methodology will remain compliant until that certificate expires.

With the deadline now confirmed, landlords should not wait. Planning improvements early will help spread costs, avoid rushed decisions, and prevent non-compliance penalties down the line.

Green Mortgage Incentives

Many mortgage lenders offer special ‘green’ mortgage products for energy-efficient homes:

  • Properties with an EPC rating of A or B often qualify
  • Some lenders also accept properties with a C rating

These green products may include lower interest rates or cashback offers.  As a part of our process, we always check your property’s EPC rating to see if you’re eligible for these incentives.

How to Obtain or Renew an EPC

Getting a new EPC is straightforward:

  • Cost: Typically, between £40 – £120
  • Timeframe: Surveyor visit required; reports usually available in 1–3 working days
  • Finding a provider: A quick Google search for “EPC assessor near me” or “get an EPC certificate” will give you a list of local accredited providers who can carry out the assessment and issue the certificate.

Improving Your Property’s EPC Rating

Each EPC includes recommendations for energy improvements, including:

  • Insulation upgrades
  • Boiler or heating system improvements
  • Double glazing
  • Renewable energy installations

These improvements not only bring your property in line with regulatory requirements, but also:

  • Reduce tenants’ energy bills
  • Attract environmentally conscious renters
  • Contribute to long-term property value

We actively encourage energy efficiency and can help direct you to trusted resources and professionals, though we don’t directly provide EPC improvement advice.

Our Approach: Mortgage Advice That Looks at the Bigger Picture

While many focus solely on rates and repayments, at Nachu Finance we take a holistic view of your property journey—from suitability and compliance, to long-term value and tenant appeal.

If the property you are considering does not have an EPC or falls short of the requirements, this is an important discussion to have before applying for a mortgage.

Frequently Asked Questions

If an EPC already exists for your property, downloading a copy is free and straightforward. Visit the government portal at https://www.gov.uk/find-energy-certificate, select the property using your postcode and door number, and confirm it is a residential property. The certificate can be viewed and downloaded instantly.

An EPC is valid for 10 years from the date of inspection. The certificate itself carries both the inspection date and the expiry date, so you can check its validity at a glance.

It depends on the type of application:

  • Buy-to-let — yes. All let properties must currently hold a minimum EPC rating of E, rising to a minimum of C from 1 October 2030. Lenders will expect to see a current, valid EPC that meets the letting requirement before approving the application.
  • Residential purchase — the seller or estate agent is legally required to provide a valid EPC, so you should expect to see one at the point of purchase.
  • Residential remortgage — there is no mandatory requirement for a valid EPC. However, we normally ask for a copy to check whether the property qualifies for a green mortgage, available for energy-efficient homes.

Yes — green mortgages are designed to encourage energy-efficient homes, typically offering lower rates or cashback. Depending on the lender, they are available for properties rated A–B, and in some cases A–C. If your property holds one of these ratings, we always check whether the lender we are recommending offers a green product you could benefit from.

Getting a new one is simple. A new EPC typically costs £40–£120, requires a short assessor visit, and the report is usually issued within 1–3 working days. A quick search for “EPC assessor near me” will list local accredited providers who can carry out the assessment and issue the certificate.

Mortgage Planning That Goes Beyond the Basics

If you’re buying or refinancing a property and want mortgage advice that factors in more than just numbers—you’re in the right place. At Nachu Finance, we’ll help ensure every aspect of your mortgage journey is well thought through, including EPC compliance and opportunities for green incentives.

Contact us today to benefit from whole-of-market advice, experience-driven insights, and a tech-savvy, transparent approach.

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Continue Building Your Landlord Best Practices

Personal guarantee explained infographic on a chalkboard, outlining why mortgage lenders request a personal guarantee and what it means for borrowers seeking limited company mortgage finance.

Testmonials

Enquiry Form

Get in Touch with Us for Personalized Finance Assistance

Please enable JavaScript in your browser to complete this form.
=

Personal Guarantee for Limited Company Mortgages

When buying a buy-to-let property through a limited company, there are a few additional steps compared to purchasing your personal name.

One of the most important — and often least understood — is the personal guarantee, which we deal with regularly as part of Setting Up and Navigating Limited Company Mortgages .

Personal guarantee explained infographic on a chalkboard, outlining why mortgage lenders request a personal guarantee and what it means for borrowers seeking limited company mortgage finance.

If you’ve already read our guide on limited company mortgages, you’ll know that a limited company is treated as a separate legal entity from the individuals behind it — its directors and shareholders. This separation is one of the key reasons investors choose this structure, particularly for tax efficiency and long-term planning. If you are still deciding whether a limited company is the right structure for you, you may find our guide helpful.

However, this same principle creates a challenge for mortgage lenders.

The mortgage is issued to the limited company, but the lender’s assessment is based on the individuals behind it — their credit profile, income, and overall financial position. In practice, the company is the borrower, but the strength of the application comes from the people running it.

From the lender’s perspective, this creates a gap. If the company is a separate legal entity, how can they ensure that the individuals they have assessed remain accountable if the mortgage is not repaid?

This is where the personal guarantee comes in.

What is a Personal Guarantee?

In simple terms, a personal guarantee is a legal commitment made by the directors and, in some cases, shareholders of a limited company to the mortgage lender.

It confirms that if the company is unable to repay the mortgage, those individuals will step in and take personal responsibility for the debt.

Although the mortgage is in the company’s name, the personal guarantee ensures that the lender ultimately has recourse to the individuals behind it. This requirement applies whether you are purchasing a new asset or transferring an existing property into a limited company .This is why it forms a standard part of almost all limited company buy-to-let mortgages.

Why Lenders Require a Personal Guarantee

In most cases, limited company buy-to-let mortgages are taken out through newly set up Special Purpose Vehicles (SPVs). While this is perfectly acceptable to lenders, a new company will not have any financial track record of its own.

As a result, lenders are not relying on the company’s history when deciding. Instead, they are lending primarily based on the strength of the individuals behind it.

However, because the mortgage is in the name of the limited company, the lender cannot automatically pursue the directors personally if the mortgage is not repaid — unless a personal guarantee is in place.

Without a personal guarantee, the lender’s only recourse in a default would be against the company itself and the property securing the loan.

The personal guarantee provides the additional security of being able to pursue the directors and relevant shareholders personally if required. It ensures that the individuals who were assessed at application stage remain accountable for the borrowing.

It is important to understand that this is standard practice. Personal guarantees are a normal and expected part of limited company buy-to-let mortgages, particularly where the company is newly established.

Getting the structure right from the outset is important, which is why specialist professional advice on property tax decisions matters from the start. This helps ensure the balance between liability protection and long-term tax efficiency is considered before any property purchases are made.

Independent Legal Advice: What It Is and Why It Is Required

Independent legal advice — often referred to as ILA — is a mandatory part of the personal guarantee process.

For a personal guarantee to be legally valid, and for the lender to be protected from any future challenge, each director and relevant shareholder who is signing the guarantee must receive independent legal advice from a qualified solicitor.

The solicitor’s role is to ensure that the individual fully understands what they are signing and the legal implications.

The key word here is independent.

The solicitor providing this advice must be separate from the firm acting on the property purchase. This is because the solicitors handling the purchase are acting for the limited company, whereas the personal guarantee is being given by the individuals behind it. Legally, there are two different parties.

From the lender’s perspective, it is important that this advice is given independently, confirming that the personal guarantee has been properly explained and understood.

As part of this process, the solicitor will talk through the personal guarantee in detail and confirm that the individual understands they are giving a personal commitment for a loan taken out by the company, against a property that is owned in the company’s name — not in their personal name.

They will also verify the identity of the individual signing and will need to review the mortgage offer and the personal guarantee documentation.

Once the advice has been given, the solicitor will witness and countersign the relevant documents and forward the completed set to the solicitors acting on the purchase, so that the transaction can proceed.

It’s worth noting that most firms acting on the purchase will not provide independent legal advice themselves, even if asked. This is because doing so would create a conflict of interest, given that they are acting for the company in the transaction.

It is important to understand that independent legal advice is not a formality. It is a proper legal appointment with real accountability for the solicitor. The individual signing the guarantee is expected to engage with the advice and confirm their understanding, so that there can be no uncertainty about what has been agreed.

The Process Step by Step

The personal guarantee and independent legal advice process follows a clear sequence. While there are a few steps involved, it is generally straightforward when planned in advance.

A 5-step infographic showing the personal guarantee process for limited company mortgages, from mortgage offer and independent legal advice to signing the guarantee and property completion.

The above infographic outlines the five key stages of the personal guarantee process, from receiving a mortgage offer to completing a limited company property purchase.

Step 1 — Identify your ILA solicitor in advance

Not all legal firms offer independent legal advice for personal guarantees, so it is important to identify a solicitor who provides this service before you need them urgently.

We have worked with clients who have successfully used specific firms for this, and we are happy to share those details if helpful. At this stage, it is also sensible to obtain a fee quote so that you know what to expect.

Step 2 — Wait for the mortgage offer

The process cannot begin until the mortgage offer has been issued.

This is because the mortgage offer contains the specific loan details and the personal guarantee documentation. Without these, the solicitor cannot complete the advice or the signing.

While you can identify your solicitor and agree on fees in advance, the formal process can only begin once the offer is in hand.

Step 3 — Provide documents to your ILA solicitor

Once the mortgage offer is issued, you will need to provide your ILA solicitor with the required documents.

This will typically include proof of identity (such as a passport or driving licence), the mortgage offer, the personal guarantee document, and the independent legal advice certificate. The solicitor will confirm exactly what is needed.

Step 4 — Attend the ILA appointment

The appointment itself can be carried out either face to face or virtually, depending on the solicitor and lender (covered in the next section).

During the appointment, the solicitor will talk through the personal guarantee and its implications, confirm that you understand what you are signing, and then complete the signing and witnessing of the documents.

Once completed, the solicitor will forward the countersigned documents to the solicitors acting on the purchase.

Step 5 — Completion

The solicitors handling the purchase will not be able to proceed to exchange and completion until the signed personal guarantee and independent legal advice documents have been received.

This is a hard requirement. Exchange and completion cannot take place without it, so it is important to plan this step in a good time.

Face – to- Face vs Virtual Appointments

Historically, independent legal advice appointments were conducted face to face. In recent years, many solicitors now offer virtual appointments via platforms such as Teams or Zoom, and many lenders are comfortable with this approach.

However, there are a few important points to be aware of.

Before proceeding with a virtual appointment, it is important to confirm that both your ILA solicitor and your mortgage lender will accept a virtually signed personal guarantee and ILA certificate. This should not be assumed, as requirements can vary.

With virtual appointments, documents will typically need to be posted between parties for signing and witnessing. This can add time to the process, particularly where original documents are required.

That said, virtual appointments are now common, and, with the right combination of lender and solicitor, can be both time and cost efficient.

If there is any uncertainty, a face-to-face appointment remains the more straightforward option.

Who Needs to Provide a Personal Guarantee?

In most cases, the mortgage lender will require a personal guarantee from all directors of the limited company.

In addition, majority shareholders who are named on the mortgage application will usually also be required to provide a personal guarantee and receive independent legal advice.

Generally, anyone who is an applicant on the mortgage should expect to provide a personal guarantee. In practice, this typically ranges from one to four individuals.

Minority shareholders who are not part of the mortgage application will generally not be required to sign. However, this can vary depending on the lender, so it is important to confirm this at the application stage.

It is also important to understand that it is not sufficient for just one director to sign on behalf of others. Mortgage lenders require each relevant individual — directors and applicable shareholders — to provide a personal guarantee in their own name. This cannot be combined or delegated.

Does Signing a Personal Guarantee Affect Personal Borrowing Capacity?

This is a question client often have, even if they do not always ask it directly.

The short answer is that a personal guarantee does not typically impact your personal borrowing capacity in a direct way. Most personal credit decisions — including loans, credit cards, and residential mortgages — are based on your individual
credit profile. A personal guarantee on a limited company mortgage does not usually appear as a direct liability in that assessment.

However, there is an indirect point to be aware of.

When applying for further buy-to-let borrowing — whether personally or through a limited company — lenders will take into account the properties held within the limited company as part of your overall portfolio. This is the case regardless of the personal guarantee itself.

In practice, as buy-to-let mortgages are generally structured to be self-funding through rental income, this is usually manageable. However, it is important to understand that the limited company portfolio will be visible to lenders when assessing any future applications.

Cost and Timeframe

Two of the most common questions around personal guarantees and independent legal advice are cost and timing. It is important to understand both, as they form a key part of planning your purchase.

Cost

The cost of independent legal advice varies between solicitors and will depend on whether the appointment is carried out face to face or virtually.

As a guide, fees typically range from £250 to £750 plus VAT per director.

While the process may appear relatively straightforward, the fee reflects the level of responsibility the solicitor is taking on. They are required to verify identity, review documentation, provide formal advice, and retain records of the meeting, and the advice given.

They also carry ongoing legal accountability for this work and may be held liable if the process is later challenged. This is why the cost is charged at this level, even though the appointment itself may be relatively short.

If helpful, you can search for solicitors who offer independent legal advice for personal guarantees. We have also worked with firms that clients have used successfully and are happy to share details on request.

Timeframe

In theory, the process can be completed in a single day once the mortgage offer has been issued and the solicitor has all the required documents.

In practice, it is sensible to allow around two weeks from the date the mortgage offer is received.

This allows time to instruct the solicitor, complete anti-money laundering checks, gather documents, arrange the appointment, and allow for any postal time where documents need to be physically signed.

Recommendation

Plan for around two weeks between receiving the mortgage offer and having the completed personal guarantee and ILA documents with your purchase solicitors. Do not leave this to the last minute. Exchange and completion cannot proceed without it.

Buying a Second Property in the Same Limited Company

A question that often comes up, particularly from more experienced landlords, is whether a personal guarantee needs to be provided again when purchasing an additional property through the same limited company.

In most cases, the answer is yes.

Even where the same directors are buying a second property through the same company, lenders will typically require a fresh personal guarantee for each mortgage they issue.

This is because the personal guarantee is both lender-specific and property-specific. It is tied to that particular lender mortgage on that specific property and does not carry over automatically to any new borrowing.

In practice, it is very rarely possible to avoid providing a personal guarantee for a limited company mortgage. As a general rule, you should expect a personal guarantee to be required for each property purchase made through the limited company.

What Happens if a Director Leaves or is Replaced?

In a limited company mortgage, the directors are effectively the applicants. It is their income, credit profile, and deposit that the lender has assessed when approving the mortgage.

Because of this, changing the directorship of the company mid-term is not straightforward. It is not possible to simply add or remove a director without involving the mortgage lender.

If the directorship or shareholding structure needs to change, the lender must be informed and their consent obtained. In many cases, this may require moving the mortgage to a new lender entirely. The new directors would then go through the full application process, including underwriting, personal guarantees, and independent legal advice.

A helpful way to think about this is to compare it to a standard buy-to-let mortgage. Just as you cannot replace a named applicant in mid-term without going back to the lender, the same principle applies here. The lender’s decision is based on the specific individuals assessed at the time of application.

If a change in directorship is being considered for any reason, it is important to speak to your mortgage broker first to understand the lender’s position before making any changes at Companies House.

Remortgages and Changing Lenders

Personal guarantees are lender specific.

The guarantee provided to one lender when the property is purchased does not transfer to another lender if the mortgage is later remortgaged.

If the mortgage remains with the same lender, a fresh personal guarantee will not usually be required.

However, if the remortgage involves moving to a new lender, the directors will need to provide a new personal guarantee to that lender. This will also require a fresh round of independent legal advice.

This is worth factoring into both the cost and timeline when planning a remortgage to a new lender.

Happy to Help You Navigate Ltd Company Mortgages

Buying through a limited company involves more moving parts than a standard buy-to- let purchase, and the personal guarantee process is just one part of that.

From identifying the right lender, to managing the mortgage offer, to guiding clients through the independent legal advice and personal guarantee requirements, we support the process end to end.

If you are planning a limited company buy-to-let purchase and would like guidance through the process, we are always happy to help.

Frequently Asked Questions

While it can be completed in a single day once all documents are available, we recommend allowing around two weeks from the date the mortgage offer is issued.

If the appointment is virtual, additional time may be required for documents to be posted between parties.

Fees typically range from £250 to £750 plus VAT per director, depending on the solicitor and whether the appointment is face to face or virtual.

The formal process can only begin once the mortgage offer has been issued.

However, you can — and should — identify your ILA solicitor, agree fees, and understand the process in advance. The personal guarantee must be completed before exchange of contracts.

All directors of the limited company, and majority shareholders who are named on the mortgage application.

It is not possible for just one director to sign on behalf of others.

No. The personal guarantee and independent legal advice documents are a condition of the mortgage offer. 

The solicitors acting on the purchase cannot proceed to exchange or completion until these have been received in full.

No. Mortgage lenders require the ILA to be provided by a completely separate firm of solicitors.

Most firms acting on a purchase will not provide ILA themselves due to the conflict of interest this creates.

A personal guarantee is lender-specific and property-specific.

You will typically need to provide a fresh personal guarantee for each property purchased through the limited company.

If you remortgage and remain with the same lender, a new guarantee is not usually required. If you move to a new lender, a fresh guarantee will be needed.

Many solicitors now offer virtual ILA appointments via Teams or Zoom, and many lenders will accept this.

However, it is important to confirm with both your ILA solicitor and your mortgage lender before proceeding, as not all lenders accept virtually signed documents.

Picture of About the Author

About the Author

Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.

Picture of Business Profile

Business Profile

Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.

Continue Building Your Limited Company Property Strategy