Testmonials
Enquiry Form
Get in Touch with Us for Personalized Finance Assistance
Let to Buy Mortgage Explained: How It Works & Key Considerations
- Date Published : September 02, 2026
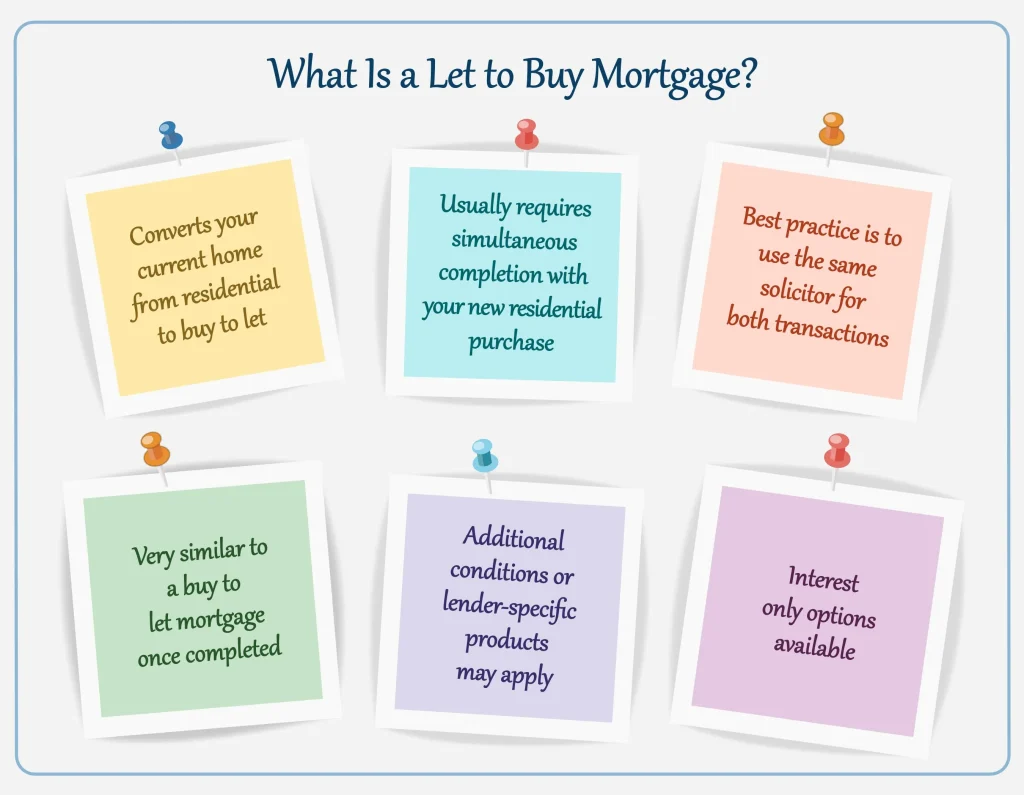
A Let to Buy mortgage is when you remortgage your current residential property onto a buy to let mortgage so that you can move into a new residential home without selling your existing one. This structure enables homeowners to keep their current property as an investment, rent it out, and at the same time proceed with the purchase of a new residential property.
What makes Let to Buy slightly different from a standard buy to let remortgage is the connected home move. You are turning your present home into a rental property specifically because you are purchasing and moving into a new residence. This is why lenders treat Let to Buy as a distinct category with its own conditions.
Why a Let to Buy Mortgage Exists
A Let to Buy mortgage is often used when:
- You wish to keep your existing home as an investment property
- You need to release equity from the current home to help fund the deposit for your onward purchase
- You prefer not to sell the property but require a mortgage that allows you to legally let the property out
Once the Let to Buy mortgage completes, the lender expects that you no longer live in that property.
Simultaneous Transactions
A key concept in Let to Buy applications
Most Let to Buy transactions require simultaneous completion between:
- The Let to Buy remortgage of the existing home
- The purchase of the new residential property
Lenders expect both to complete together because:
- Once they issue a Let to Buy mortgage, you are no longer permitted to occupy the former home.
- If you are raising funds from the existing property to help with the new purchase, the purchase cannot complete unless the Let to Buy remortgage completes.
- The two transactions are financially and legally dependent on each other, similar to how a sale and purchase work together on the same day.
This simultaneous structure ensures that the equity release, legal change of status, and occupation rules all align within the same completion window.
When You Do Not Need a Simultaneous Transaction
A simultaneous completion is not required if you do not need to release funds from your current home for the new purchase. In that case:
- You may complete the new residential purchase first
- Move into the new property
- Prepare the former property to be rented out
- Then apply for either:
- A Let to Buy remortgage at a later date, or
- Obtain consent to let temporarily and switch to a buy to let mortgage later
When you are planning to buy first and rent out the current residential property at a later time you may need to get evidence of the expected rental income from an ARLA recognised letting agent for the purpose of the new mortgage on the property you are going to purchase. This letter would be needed to evidence that rent can offset the mortgage commitment on the current residential mortgage.
What you cannot do is complete the Let to Buy remortgage first, remain living in the property, and delay the residential purchase. The occupation rules do not allow this.
Transferring the Former Residential Property into a Limited Company
An alternative to retaining the former residential property under a Let to Buy structure is to transfer the property into a limited company and then proceed with the new residential purchase separately.
This approach can be suitable in certain circumstances, particularly for clients considering long-term property investment through a company. However, it is not appropriate for everyone and requires careful consideration.
While Capital Gains Tax does not usually apply (subject to conditions being met and only for the period you have occupied the property) when transferring a former main residence due to principal private residence relief, Stamp Duty Land Tax (SDLT) is a key factor. The limited company is treated as a separate buyer, meaning SDLT is calculated on the full market value of the property and will include the additional property stamp duty (higher rate surcharge).
There are also additional costs and practical implications, including:
- Two legal transactions (sale from personal names and purchase by the company)
- Two sets of solicitor fees
- Valuation and mortgage arrangement costs
- Ongoing company running and compliance expenses
For some clients, particularly those buying a significantly more expensive residential property than the value of their current property, this structure can work well. For others, it may add complexity and cost without delivering sufficient benefit. The decision should always be assessed in the context of personal circumstances, long-term plans, and overall affordability.
You can read more in our detailed article on transferring property from personal name to a limited company, including the Real life Case Study: A Former Home Becomes a Tax-Efficient Investment, which explores this option in greater depth.
Prakash and Meena
Prakash and Meena lived in a two-bedroom flat that no longer met their growing family’s needs. They found a three-bedroom house they wished to purchase, but they did not want to sell their existing flat as they viewed it as a strong long-term investment.
They required an additional £50,000 from the flat to complete the new purchase.
We arranged:
- A Let to Buy remortgage with BM Solutions on an interest-only basis, supported by the expected rental income
- A new residential mortgage with Halifax
Both transactions completed on 12 June.
The solicitor received the Halifax mortgage funds first. On the completion day (12th June), the solicitor:
- Drew down the BM Solutions Let to Buy mortgage
- Repaid the existing Santander residential mortgage
- Used the remaining £50,000 toward the deposit for the new purchase
Because the clients needed the equity release, the simultaneous completion structure worked perfectly.
Had they not required equity from the flat, they could have purchased the new home first and dealt with the remortgage later.
Frequently Asked Questions
The mortgage conditions stipulate that once the Let to Buy mortgage completes and you own your new residential home, you must no longer occupy the former property.
In practice, lenders understand there may be a short transition period to clean, prepare, or repair the property before letting it. The lenders generally allow a reasonable period to prepare the property for letting, but the clear expectation is that the property becomes let-ready as soon as reasonably possible.
It is also in your interest financially to avoid paying two full residential-style mortgages longer than necessary.
Lenders know the property is not yet let.
You can research the likely market rental income using letting agents or online portals.
The lender’s surveyor (valuer) will confirm:
- The property value
- The expected rental income
Your mortgage offer will be based on the valuer’s confirmed rental assessment.
Once the Let to Buy mortgage starts, there is effectively no practical difference. The property is treated as a buy to let property.
The differences arise before completion:
- The property is not yet let
- There is a connected residential purchase
- Some lenders have a dedicated product range or slightly different criteria for Let to Buy
- Some lenders who offer buy to let mortgages may not offer let to buy mortgages and others may have additional conditions that apply for a let to buy mortgage
After completion, it functions the same as any buy to let mortgage.
Yes.
Although buy to let mortgages are generally unregulated, a Let to Buy remortgage is treated as consumer buy to let because the loan relates to a property that was your main residence.
You can still choose interest only or repayment options, but the advice and application fall under regulated mortgage rules.
Yes.
Although residential mortgages are typically repayment-based, lenders are comfortable offering interest only on Let to Buy mortgages, provided it suits your circumstances and the rental income supports the structure.
Legally no, but practically it is strongly recommended.
Using one solicitor avoids:
- Delays in transferring funds
- Coordination gaps between the two transactions
- Increased administrative costs
A single solicitor ensures the simultaneous completion can progress smoothly.
About the Author
Sekkappan Alagu is the Founder of Nachu Finance Ltd, established in 2006. With an early career in journalism and publishing, he brings clarity and structured thinking to complex financial topics. Through the Nachu Finance Blog and Knowledge Hub, he shares insights drawn from nearly two decades of client advisory experience, helping readers make informed decisions and understand best practices in mortgages, protection and long-term financial planning.
Business Profile
Nachu Finance Ltd is a directly authorised FCA-regulated firm providing mortgage, insurance and estate planning advice to clients across the UK. The firm takes a holistic approach — considering protection, tax efficiency and long-term planning alongside property finance — maintaining high regulatory standards while keeping advice clear and easy to follow. To learn more about the firm's background and story, visit the About Nachu Finance page.
From Homeowner to Landlord: What Comes Next